Credit card interest margin
In August 2026, the average credit card APR on accounts charged interest was 22.36%: 15.61 percentage points above the prime rate and 18.73 percentage points above the Fed funds rate. Both gaps are the widest since the Federal Reserve’s card rate series began in November 1994. In 2024 the CFPB called a 14.3% margin over prime an all-time high; it is higher now.
The margin in August 2026
- Card APR minus the prime rate
- 15.61 ptsup 0.28 percentage points in a yearThe highest on record
- Card APR minus the Fed funds rate
- 18.73 ptsup 0.23 percentage points in a yearThe highest on record
- Average card APR, accounts charged interest
- 22.36%Federal Reserve G.19
- Prime rate · Fed funds rate
- 6.75% · 3.63%Monthly averages, Federal Reserve H.15
How has the credit card margin changed since 1994?
The margin over prime was 7.62 percentage points in November 1994 and 10.26 percentage points in August 2016. In August 2026 it was 15.61 percentage points. When the Fed cuts rates, the prime rate follows it within days, but the average card APR has fallen more slowly, so the margin widens; it widened after the cuts of 2001, 2008 and 2020, and again since 2024.
- APR minus prime
- APR minus Fed funds
Source: BestCreditCards calculation from Federal Reserve G.19 (series TERMCBCCINTNS) and H.15 (MPRIME, FEDFUNDS), via FRED, saved October 14, 2026. Card rates are surveyed in February, May, August and November.
Show the data (128 rows)
| Month | Card APR | Prime | Fed funds | APR − prime | APR − Fed funds |
|---|---|---|---|---|---|
| August 2026 | 22.36 | 6.75 | 3.63 | 15.61 | 18.73 |
| May 2026 | 22.15 | 6.75 | 3.63 | 15.40 | 18.52 |
| February 2026 | 21.52 | 6.75 | 3.64 | 14.77 | 17.88 |
| November 2025 | 22.30 | 7.00 | 3.88 | 15.30 | 18.42 |
| August 2025 | 22.83 | 7.50 | 4.33 | 15.33 | 18.50 |
| May 2025 | 22.25 | 7.50 | 4.33 | 14.75 | 17.92 |
| February 2025 | 21.91 | 7.50 | 4.33 | 14.41 | 17.58 |
| November 2024 | 22.80 | 7.81 | 4.64 | 14.99 | 18.16 |
| August 2024 | 23.37 | 8.50 | 5.33 | 14.87 | 18.04 |
| May 2024 | 22.78 | 8.50 | 5.33 | 14.28 | 17.45 |
| February 2024 | 22.63 | 8.50 | 5.33 | 14.13 | 17.30 |
| November 2023 | 22.75 | 8.50 | 5.33 | 14.25 | 17.42 |
| August 2023 | 22.77 | 8.50 | 5.33 | 14.27 | 17.44 |
| May 2023 | 22.16 | 8.23 | 5.06 | 13.93 | 17.10 |
| February 2023 | 20.92 | 7.74 | 4.57 | 13.18 | 16.35 |
| November 2022 | 20.40 | 6.95 | 3.78 | 13.45 | 16.62 |
| August 2022 | 18.43 | 5.50 | 2.33 | 12.93 | 16.10 |
| May 2022 | 16.65 | 3.94 | 0.77 | 12.71 | 15.88 |
| February 2022 | 16.17 | 3.25 | 0.08 | 12.92 | 16.09 |
| November 2021 | 16.44 | 3.25 | 0.08 | 13.19 | 16.36 |
| August 2021 | 17.13 | 3.25 | 0.09 | 13.88 | 17.04 |
| May 2021 | 16.30 | 3.25 | 0.06 | 13.05 | 16.24 |
| February 2021 | 15.91 | 3.25 | 0.08 | 12.66 | 15.83 |
| November 2020 | 16.28 | 3.25 | 0.09 | 13.03 | 16.19 |
| August 2020 | 16.43 | 3.25 | 0.10 | 13.18 | 16.33 |
| May 2020 | 15.78 | 3.25 | 0.05 | 12.53 | 15.73 |
| February 2020 | 16.61 | 4.75 | 1.58 | 11.86 | 15.03 |
| November 2019 | 16.88 | 4.75 | 1.55 | 12.13 | 15.33 |
| August 2019 | 16.97 | 5.25 | 2.13 | 11.72 | 14.84 |
| May 2019 | 17.14 | 5.50 | 2.39 | 11.64 | 14.75 |
| February 2019 | 16.91 | 5.50 | 2.40 | 11.41 | 14.51 |
| November 2018 | 16.86 | 5.25 | 2.20 | 11.61 | 14.66 |
| August 2018 | 16.46 | 5.00 | 1.91 | 11.46 | 14.55 |
| May 2018 | 15.54 | 4.75 | 1.70 | 10.79 | 13.84 |
| February 2018 | 15.32 | 4.50 | 1.42 | 10.82 | 13.90 |
| November 2017 | 14.99 | 4.25 | 1.16 | 10.74 | 13.83 |
| August 2017 | 14.89 | 4.25 | 1.16 | 10.64 | 13.73 |
| May 2017 | 14.00 | 4.00 | 0.91 | 10.00 | 13.09 |
| February 2017 | 13.86 | 3.75 | 0.66 | 10.11 | 13.20 |
| November 2016 | 13.61 | 3.50 | 0.41 | 10.11 | 13.20 |
| August 2016 | 13.76 | 3.50 | 0.40 | 10.26 | 13.36 |
| May 2016 | 13.35 | 3.50 | 0.37 | 9.85 | 12.98 |
| February 2016 | 13.51 | 3.50 | 0.38 | 10.01 | 13.13 |
| November 2015 | 13.70 | 3.25 | 0.12 | 10.45 | 13.58 |
| August 2015 | 13.93 | 3.25 | 0.14 | 10.68 | 13.79 |
| May 2015 | 13.49 | 3.25 | 0.12 | 10.24 | 13.37 |
| February 2015 | 13.53 | 3.25 | 0.11 | 10.28 | 13.42 |
| November 2014 | 13.68 | 3.25 | 0.09 | 10.43 | 13.59 |
| August 2014 | 13.18 | 3.25 | 0.09 | 9.93 | 13.09 |
| May 2014 | 12.74 | 3.25 | 0.09 | 9.49 | 12.65 |
| February 2014 | 13.14 | 3.25 | 0.07 | 9.89 | 13.07 |
| November 2013 | 12.89 | 3.25 | 0.08 | 9.64 | 12.81 |
| August 2013 | 13.11 | 3.25 | 0.08 | 9.86 | 13.03 |
| May 2013 | 12.76 | 3.25 | 0.11 | 9.51 | 12.65 |
| February 2013 | 13.02 | 3.25 | 0.15 | 9.77 | 12.87 |
| November 2012 | 12.81 | 3.25 | 0.16 | 9.56 | 12.65 |
| August 2012 | 13.21 | 3.25 | 0.13 | 9.96 | 13.08 |
| May 2012 | 12.76 | 3.25 | 0.16 | 9.51 | 12.60 |
| February 2012 | 13.04 | 3.25 | 0.10 | 9.79 | 12.94 |
| November 2011 | 12.78 | 3.25 | 0.08 | 9.53 | 12.70 |
| August 2011 | 13.08 | 3.25 | 0.10 | 9.83 | 12.98 |
| May 2011 | 13.06 | 3.25 | 0.09 | 9.81 | 12.97 |
| February 2011 | 13.44 | 3.25 | 0.16 | 10.19 | 13.28 |
| November 2010 | 13.67 | 3.25 | 0.19 | 10.42 | 13.48 |
| August 2010 | 14.22 | 3.25 | 0.19 | 10.97 | 14.03 |
| May 2010 | 14.48 | 3.25 | 0.20 | 11.23 | 14.28 |
| February 2010 | 14.67 | 3.25 | 0.13 | 11.42 | 14.54 |
| November 2009 | 14.37 | 3.25 | 0.12 | 11.12 | 14.25 |
| August 2009 | 14.90 | 3.25 | 0.16 | 11.65 | 14.74 |
| May 2009 | 14.43 | 3.25 | 0.18 | 11.18 | 14.25 |
| February 2009 | 13.54 | 3.25 | 0.22 | 10.29 | 13.32 |
| November 2008 | 13.36 | 4.00 | 0.39 | 9.36 | 12.97 |
| August 2008 | 13.64 | 5.00 | 2.00 | 8.64 | 11.64 |
| May 2008 | 13.51 | 5.00 | 1.98 | 8.51 | 11.53 |
| February 2008 | 13.77 | 6.00 | 2.98 | 7.77 | 10.79 |
| November 2007 | 14.38 | 7.50 | 4.49 | 6.88 | 9.89 |
| August 2007 | 15.24 | 8.25 | 5.02 | 6.99 | 10.22 |
| May 2007 | 14.47 | 8.25 | 5.25 | 6.22 | 9.22 |
| February 2007 | 14.64 | 8.25 | 5.26 | 6.39 | 9.38 |
| November 2006 | 15.09 | 8.25 | 5.25 | 6.84 | 9.84 |
| August 2006 | 14.67 | 8.25 | 5.25 | 6.42 | 9.42 |
| May 2006 | 14.77 | 7.93 | 4.94 | 6.84 | 9.83 |
| February 2006 | 14.38 | 7.50 | 4.49 | 6.88 | 9.89 |
| November 2005 | 14.49 | 7.00 | 4.00 | 7.49 | 10.49 |
| August 2005 | 14.75 | 6.44 | 3.50 | 8.31 | 11.25 |
| May 2005 | 14.81 | 5.98 | 3.00 | 8.83 | 11.81 |
| February 2005 | 14.13 | 5.49 | 2.50 | 8.64 | 11.63 |
| November 2004 | 13.92 | 4.93 | 1.93 | 8.99 | 11.99 |
| August 2004 | 13.60 | 4.43 | 1.43 | 9.17 | 12.17 |
| May 2004 | 12.93 | 4.00 | 1.00 | 8.93 | 11.93 |
| February 2004 | 12.42 | 4.00 | 1.01 | 8.42 | 11.41 |
| November 2003 | 12.93 | 4.00 | 1.00 | 8.93 | 11.93 |
| August 2003 | 13.13 | 4.00 | 1.03 | 9.13 | 12.10 |
| May 2003 | 12.89 | 4.25 | 1.26 | 8.64 | 11.63 |
| February 2003 | 11.96 | 4.25 | 1.26 | 7.71 | 10.70 |
| November 2002 | 12.78 | 4.35 | 1.34 | 8.43 | 11.44 |
| August 2002 | 13.29 | 4.75 | 1.74 | 8.54 | 11.55 |
| May 2002 | 13.36 | 4.75 | 1.75 | 8.61 | 11.61 |
| February 2002 | 13.00 | 4.75 | 1.74 | 8.25 | 11.26 |
| November 2001 | 13.90 | 5.10 | 2.09 | 8.80 | 11.81 |
| August 2001 | 14.67 | 6.67 | 3.65 | 8.00 | 11.02 |
| May 2001 | 14.65 | 7.24 | 4.21 | 7.41 | 10.44 |
| February 2001 | 14.63 | 8.50 | 5.49 | 6.13 | 9.14 |
| November 2000 | 15.26 | 9.50 | 6.51 | 5.76 | 8.75 |
| August 2000 | 15.37 | 9.50 | 6.50 | 5.87 | 8.87 |
| May 2000 | 14.76 | 9.24 | 6.27 | 5.52 | 8.49 |
| February 2000 | 14.30 | 8.73 | 5.73 | 5.57 | 8.57 |
| November 1999 | 14.78 | 8.37 | 5.42 | 6.41 | 9.36 |
| August 1999 | 14.80 | 8.06 | 5.07 | 6.74 | 9.73 |
| May 1999 | 14.94 | 7.75 | 4.74 | 7.19 | 10.20 |
| February 1999 | 14.73 | 7.75 | 4.76 | 6.98 | 9.97 |
| November 1998 | 15.73 | 7.89 | 4.83 | 7.84 | 10.90 |
| August 1998 | 15.84 | 8.50 | 5.55 | 7.34 | 10.29 |
| May 1998 | 15.70 | 8.50 | 5.49 | 7.20 | 10.21 |
| February 1998 | 15.34 | 8.50 | 5.51 | 6.84 | 9.83 |
| November 1997 | 15.74 | 8.50 | 5.52 | 7.24 | 10.22 |
| August 1997 | 15.79 | 8.50 | 5.54 | 7.29 | 10.25 |
| May 1997 | 15.72 | 8.50 | 5.50 | 7.22 | 10.22 |
| February 1997 | 15.15 | 8.25 | 5.19 | 6.90 | 9.96 |
| November 1996 | 15.52 | 8.25 | 5.31 | 7.27 | 10.21 |
| August 1996 | 15.66 | 8.25 | 5.22 | 7.41 | 10.44 |
| May 1996 | 15.33 | 8.25 | 5.24 | 7.08 | 10.09 |
| February 1996 | 15.42 | 8.25 | 5.22 | 7.17 | 10.20 |
| November 1995 | 15.74 | 8.75 | 5.80 | 6.99 | 9.94 |
| August 1995 | 15.90 | 8.75 | 5.74 | 7.15 | 10.16 |
| May 1995 | 16.26 | 9.00 | 6.01 | 7.26 | 10.25 |
| February 1995 | 15.28 | 9.00 | 5.92 | 6.28 | 9.36 |
| November 1994 | 15.77 | 8.15 | 5.29 | 7.62 | 10.48 |
Why don’t credit card rates go down when the Fed cuts?
They do go down, but by less than the Fed’s rate. Since August 2024, the Fed funds rate has fallen 1.70 percentage points, while the average card APR on accounts charged interest has fallen 1.01 percentage points: 59% of the cut so far. The difference is the margin, which rose from 14.87 percentage points to 15.61 percentage points over prime in the same period.
Most card APRs are variable and move with the prime rate, which moves with the Fed’s rate. Of the 141 US cards in our records, 108 tie it to the prime rate in their own pricing terms, most in these words: “This APR will vary with the market based on the Prime Rate.” The average falls by less because the margin above prime has widened. These figures can’t show why; the CFPB’s 2024 analysis found that issuers raised their APR margins (see below). For the underlying rate series, see average credit card APRs over time.
| Cycle | Fed funds rate | Average card APR | Share passed on | Margin over prime |
|---|---|---|---|---|
| November 2000 to November 2003 | 6.51% → 1.00% (-5.51) | 15.26% → 12.93% (-2.33) | 42% | 5.76 → 8.93 pts |
| February 2007 to November 2009 | 5.26% → 0.12% (-5.14) | 14.64% → 14.37% (-0.27) | 5% | 6.39 → 11.12 pts |
| February 2019 to May 2020 | 2.40% → 0.05% (-2.35) | 16.91% → 15.78% (-1.13) | 48% | 11.41 → 12.53 pts |
| August 2024 to August 2026 (so far) | 5.33% → 3.63% (-1.70) | 23.37% → 22.36% (-1.01) | 59% | 14.87 → 15.61 pts |
Our calculation from the Federal Reserve’s series. Each cycle runs from the last card-survey month at the Fed funds rate’s peak, before the first cut, to the first month at its low, or to the latest reading if cuts may continue. Card rates are surveyed every three months, so the months are the nearest survey months, not the dates of the Fed’s decisions.
What margins do credit card issuers set?
Across the 106 US cards in our records whose APR follows the prime rate, from 25 issuers, the median card’s lowest purchase APR is 12.74 percentage points above prime and its highest 21.49 percentage points. Which end you get depends on your credit. The lowest margin we found is 3.49 percentage points (Navy Federal Platinum Credit Card); the highest is 27.99 percentage points (Bilt Blue Card).
These are what issuers advertise to new applicants today, so they aren’t the same measure as the Federal Reserve’s average above, which covers existing balances. For 74 of the 106 cards, the issuer states its margin in its own terms (“Prime Rate + 18.74%”), and we quote it. For the rest, we worked the margin out as the card’s published APR minus the prime rate on the day we checked it (7.00%, between October 4, 2026 and October 22, 2026). The stated margins show that 23 cards’ published APRs were still built on an earlier prime rate of 6.75% when we checked them, so their live APRs may since have risen with the prime rate.
- 12.74 pts
- median margin at the bottom of a card’s APR range, for applicants with the best credit.
- 21.49 pts
- median margin at the top of the range, which applicants with weaker credit get.
- 106 of 141
- US cards in our records tie their APR to the prime rate in the issuer’s own words.
Source: our records of each card’s published purchase APR range, minus the prime rate on the day checked (Federal Reserve H.15). Each bar counts cards whose highest margin falls in that 2-point band (lower bound included).
| Issuer | Cards | Lowest margin | Highest margin | Stated by the issuer |
|---|---|---|---|---|
| Navy Federal Credit Union | 4 | 3.49 pts | 11.25 pts | 4 of 4 |
| Huntington Bank | 4 | 6.74 pts | 20.74 pts | 4 of 4 |
| Alliant Credit Union | 2 | 6.99 pts | 18.99 pts | 2 of 2 |
| Bank of America | 5 | 8.24 pts | 20.74 pts | No |
| Citizens | 3 | 8.74 pts | 20.74 pts | 3 of 3 |
| TD Bank | 5 | 9.99 pts | 21.74 pts | 5 of 5 |
| Truist | 3 | 9.99 pts | 20.99 pts | 3 of 3 |
| U.S. Bank | 8 | 10.24 pts | 21.74 pts | No |
| Discover | 3 | 10.74 pts | 19.74 pts | 3 of 3 |
| Goldman Sachs Bank USA, Salt Lake City Branch | 1 | 10.74 pts | 20.99 pts | 1 of 1 |
| Wells Fargo | 4 | 10.74 pts | 21.74 pts | 4 of 4 |
| PenFed Credit Union | 3 | 10.99 pts | 10.99 pts | No |
| Chase | 11 | 11.49 pts | 22.24 pts | 11 of 11 |
| Barclays | 10 | 11.74 pts | 25.49 pts | 10 of 10 |
| Capital One | 5 | 11.74 pts | 22.24 pts | 5 of 5 |
| PNC Bank | 4 | 11.74 pts | 21.74 pts | No |
| Synchrony Bank | 1 | 11.74 pts | 26.49 pts | 1 of 1 |
| American Express | 7 | 12.74 pts | 21.74 pts | 7 of 7 |
| Upgrade | 1 | 12.99 pts | 22.99 pts | No |
| Mission Lane | 4 | 13.24 pts | 27.24 pts | 4 of 4 |
| KeyBank | 2 | 13.74 pts | 20.74 pts | No |
| opensky | 3 | 17.14 pts | 21.49 pts | 3 of 3 |
| Regions Bank | 1 | 19.74 pts | 19.74 pts | 1 of 1 |
| Column N.A. | 3 | 19.99 pts | 27.99 pts | 3 of 3 |
| Credit One Bank | 9 | 22.74 pts | 22.74 pts | No |
Every card (106)
| Card | Purchase APR | Prime rate it’s built on | Margin over prime | Source of the margin | Checked |
|---|---|---|---|---|---|
| Navy Federal Platinum Credit Card Navy Federal Credit Union | 10.24%–18.00% | 6.75% | 3.49–11.25 pts | Stated by Navy Federal Credit Union | October 6, 2026 |
| Huntington Voice Credit Card® Huntington Bank | 13.74%–25.74% | 7.00% | 6.74–18.74 pts | Stated by Huntington Bank | October 6, 2026 |
| Alliant Visa® Platinum Credit Card Alliant Credit Union | 13.99%–25.99% | 7.00% | 6.99–18.99 pts | Stated by Alliant Credit Union | October 22, 2026 |
| Navy Federal cashRewards Credit Card Navy Federal Credit Union | 14.15%–18.00% | 6.75% | 7.40–11.25 pts | Stated by Navy Federal Credit Union | October 6, 2026 |
| Navy Federal cashRewards Plus Credit Card Navy Federal Credit Union | 14.15%–18.00% | 6.75% | 7.40–11.25 pts | Stated by Navy Federal Credit Union | October 6, 2026 |
| BankAmericard® Credit Card Bank of America | 15.24%–26.24% | 7.00% | 8.24–19.24 pts | APR minus prime that day | October 6, 2026 |
| Citizens Spring® World Mastercard® Citizens | 15.49%–25.49% | 6.75% | 8.74–18.74 pts | Stated by Citizens | October 6, 2026 |
| Huntington® Cashback Credit Card Huntington Bank | 15.74%–27.74% | 7.00% | 8.74–20.74 pts | Stated by Huntington Bank | October 6, 2026 |
| Huntington Voice Rewards Credit Card℠ Huntington Bank | 15.74%–27.74% | 7.00% | 8.74–20.74 pts | Stated by Huntington Bank | October 6, 2026 |
| Navy Federal Flagship Premier Visa Signature® Credit Card Navy Federal Credit Union | 15.74%–18.00% | 6.75% | 8.99–11.25 pts | Stated by Navy Federal Credit Union | October 6, 2026 |
| Alliant Cashback Visa® Signature Credit Card Alliant Credit Union | 15.99%–25.99% | 7.00% | 8.99–18.99 pts | Stated by Alliant Credit Union | October 22, 2026 |
| TD First Class℠ Visa Signature® Credit Card TD Bank | 16.74% | 6.75% | 9.99 pts | Stated by TD Bank | October 6, 2026 |
| Truist Future Credit Card Truist | 16.99%–25.99% | 7.00% | 9.99–18.99 pts | Stated by Truist | October 22, 2026 |
| U.S. Bank Shield® Visa® Card U.S. Bank | 17.24%–28.24% | 7.00% | 10.24–21.24 pts | APR minus prime that day | October 5, 2026 |
| U.S. Bank Altitude® Connect Visa Signature® Card U.S. Bank | 17.74%–27.74% | 7.00% | 10.74–20.74 pts | APR minus prime that day | October 5, 2026 |
| U.S. Bank Altitude® Go Visa Signature® Card U.S. Bank | 17.74%–27.74% | 7.00% | 10.74–20.74 pts | APR minus prime that day | October 5, 2026 |
| Discover it® Cash Back Discover | 17.74%–26.74% | 7.00% | 10.74–19.74 pts | Stated by Discover | October 6, 2026 |
| Discover it® Miles Discover | 17.74%–26.74% | 7.00% | 10.74–19.74 pts | Stated by Discover | October 6, 2026 |
| Discover it® Chrome Gas & Restaurants Discover | 17.74%–26.74% | 7.00% | 10.74–19.74 pts | Stated by Discover | October 6, 2026 |
| Bank of America® Customized Cash Rewards Credit Card Bank of America | 17.74%–27.74% | 7.00% | 10.74–20.74 pts | APR minus prime that day | October 6, 2026 |
| Bank of America® Unlimited Cash Rewards Credit Card Bank of America | 17.74%–27.74% | 7.00% | 10.74–20.74 pts | APR minus prime that day | October 6, 2026 |
| Bank of America® Travel Rewards Credit Card Bank of America | 17.74%–27.74% | 7.00% | 10.74–20.74 pts | APR minus prime that day | October 6, 2026 |
| Wells Fargo Reflect® Card Wells Fargo | 17.74%–28.49% | 7.00% | 10.74–21.49 pts | Stated by Wells Fargo | October 6, 2026 |
| TD FlexPay Credit Card TD Bank | 17.49%–27.49% | 6.75% | 10.74–20.74 pts | Stated by TD Bank | October 6, 2026 |
| Apple Card Goldman Sachs Bank USA, Salt Lake City Branch | 17.74%–27.99% | 7.00% | 10.74–20.99 pts | Stated by Goldman Sachs Bank USA, Salt Lake City Branch | October 6, 2026 |
| Citizens Summit® World Mastercard® Citizens | 17.49%–27.49% | 6.75% | 10.74–20.74 pts | Stated by Citizens | October 6, 2026 |
| U.S. Bank Cash+® Visa Signature® Card U.S. Bank | 17.99%–28.24% | 7.00% | 10.99–21.24 pts | APR minus prime that day | October 5, 2026 |
| PenFed Power Cash Rewards® Visa Signature® Card PenFed Credit Union | 17.99% | 7.00% | 10.99 pts | APR minus prime that day | October 6, 2026 |
| PenFed Platinum Rewards Visa Signature® Card PenFed Credit Union | 17.99% | 7.00% | 10.99 pts | APR minus prime that day | October 6, 2026 |
| PenFed Pathfinder Rewards® Visa Signature® Card PenFed Credit Union | 17.99% | 7.00% | 10.99 pts | APR minus prime that day | October 6, 2026 |
| Chase Freedom Unlimited® Credit Card Chase | 18.49%–27.99% | 7.00% | 11.49–20.99 pts | Stated by Chase | October 4, 2026 |
| Chase Freedom Rise® Credit Card Chase | 18.49%–27.99% | 7.00% | 11.49–20.99 pts | Stated by Chase | October 4, 2026 |
| U.S. Bank Smartly™ Visa Signature® Card U.S. Bank | 18.49%–28.49% | 7.00% | 11.49–21.49 pts | APR minus prime that day | October 5, 2026 |
| Chase Freedom Flex® Credit Card Chase | 18.49%–27.99% | 7.00% | 11.49–20.99 pts | Stated by Chase | October 6, 2026 |
| Wells Fargo Active Cash® Card Wells Fargo | 18.74%–28.74% | 7.00% | 11.74–21.74 pts | Stated by Wells Fargo | October 4, 2026 |
| Wells Fargo Autograph® Card Wells Fargo | 18.74%–28.74% | 7.00% | 11.74–21.74 pts | Stated by Wells Fargo | October 5, 2026 |
| Upromise® World Mastercard® Barclays | 18.74%–29.74% | 7.00% | 11.74–22.74 pts | Stated by Barclays | October 5, 2026 |
| Capital One VentureOne Rewards Credit Card Capital One | 18.74%–28.74% | 7.00% | 11.74–21.74 pts | Stated by Capital One | October 6, 2026 |
| Capital One Quicksilver Cash Rewards Credit Card Capital One | 18.74%–28.74% | 7.00% | 11.74–21.74 pts | Stated by Capital One | October 6, 2026 |
| PNC Cash Rewards® Visa® Credit Card PNC Bank | 18.74%–28.74% | 7.00% | 11.74–21.74 pts | APR minus prime that day | October 22, 2026 |
| PNC Cash Unlimited® Visa Signature® Credit Card PNC Bank | 18.74%–28.74% | 7.00% | 11.74–21.74 pts | APR minus prime that day | October 22, 2026 |
| TD Cash Credit Card TD Bank | 18.49%–28.49% | 6.75% | 11.74–21.74 pts | Stated by TD Bank | October 22, 2026 |
| TD Double Up℠ Credit Card TD Bank | 18.49%–28.49% | 6.75% | 11.74–21.74 pts | Stated by TD Bank | October 6, 2026 |
| PayPal Cashback Mastercard® Synchrony Bank | 18.49%–33.24% | 6.75% | 11.74–26.49 pts | Stated by Synchrony Bank | October 6, 2026 |
| Prime Visa Chase | 18.99%–27.74% | 7.00% | 11.99–20.74 pts | Stated by Chase | October 6, 2026 |
| Truist Enjoy Cash Credit Card Truist | 18.99%–27.99% | 7.00% | 11.99–20.99 pts | Stated by Truist | October 22, 2026 |
| Chase Sapphire Preferred® Credit Card Chase | 19.49%–27.74% | 7.00% | 12.49–20.74 pts | Stated by Chase | October 5, 2026 |
| Wyndham Rewards Earner® Card Barclays | 19.49%–29.99% | 7.00% | 12.49–22.99 pts | Stated by Barclays | October 5, 2026 |
| Wyndham Rewards Earner® Plus Card Barclays | 19.49%–29.99% | 7.00% | 12.49–22.99 pts | Stated by Barclays | October 5, 2026 |
| Southwest Rapid Rewards® Plus Credit Card Chase | 19.49%–27.99% | 7.00% | 12.49–20.99 pts | Stated by Chase | October 6, 2026 |
| Marriott Bonvoy Boundless® Credit Card Chase | 19.49%–27.99% | 7.00% | 12.49–20.99 pts | Stated by Chase | October 6, 2026 |
| IHG One Rewards Premier Credit Card Chase | 19.49%–27.99% | 7.00% | 12.49–20.99 pts | Stated by Chase | October 6, 2026 |
| Wells Fargo Autograph Journey℠ Card Wells Fargo | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by Wells Fargo | October 5, 2026 |
| JetBlue Card Barclays | 19.74%–29.74% | 7.00% | 12.74–22.74 pts | Stated by Barclays | October 5, 2026 |
| JetBlue Plus Card Barclays | 19.74%–29.74% | 7.00% | 12.74–22.74 pts | Stated by Barclays | October 5, 2026 |
| Breeze Easy® Visa® Credit Card Barclays | 19.74%–29.74% | 7.00% | 12.74–22.74 pts | Stated by Barclays | October 5, 2026 |
| Frontier Airlines World Mastercard® Barclays | 19.74%–29.74% | 7.00% | 12.74–22.74 pts | Stated by Barclays | October 5, 2026 |
| Chase Sapphire Reserve® Credit Card Chase | 19.74%–28.24% | 7.00% | 12.74–21.24 pts | Stated by Chase | October 6, 2026 |
| American Express® Gold Card American Express | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by American Express | October 6, 2026 |
| The Platinum Card® from American Express American Express | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by American Express | October 6, 2026 |
| Delta SkyMiles® Gold American Express Card American Express | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by American Express | October 6, 2026 |
| Delta SkyMiles® Blue American Express Card American Express | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by American Express | October 6, 2026 |
| Hilton Honors American Express Card American Express | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by American Express | October 6, 2026 |
| Hilton Honors American Express Surpass® Card American Express | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by American Express | October 6, 2026 |
| Marriott Bonvoy Bevy® American Express® Card American Express | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by American Express | October 6, 2026 |
| Capital One Venture Rewards Credit Card Capital One | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by Capital One | October 6, 2026 |
| Capital One Venture X Rewards Credit Card Capital One | 19.74%–28.74% | 7.00% | 12.74–21.74 pts | Stated by Capital One | October 6, 2026 |
| Bank of America® Premium Rewards® Credit Card Bank of America | 19.74%–27.74% | 7.00% | 12.74–20.74 pts | APR minus prime that day | October 6, 2026 |
| PNC Spend Wise® Visa® Credit Card PNC Bank | 19.74%–27.74% | 7.00% | 12.74–20.74 pts | APR minus prime that day | October 22, 2026 |
| United℠ Explorer Card Chase | 19.99%–28.49% | 7.00% | 12.99–21.49 pts | Stated by Chase | October 6, 2026 |
| Upgrade OneCard Essentials Upgrade | 19.99%–29.99% | 7.00% | 12.99–22.99 pts | APR minus prime that day | October 6, 2026 |
| Mission Lane Gold Line Visa® Mission Lane | 19.99%–33.99% | 6.75% | 13.24–27.24 pts | Stated by Mission Lane | October 6, 2026 |
| Mission Lane Silver Line Visa® Mission Lane | 19.99%–33.99% | 6.75% | 13.24–27.24 pts | Stated by Mission Lane | October 6, 2026 |
| Mission Lane Green Line Visa® Mission Lane | 19.99%–33.99% | 6.75% | 13.24–27.24 pts | Stated by Mission Lane | October 6, 2026 |
| Mission Lane Secured Visa® Mission Lane | 19.99%–33.99% | 6.75% | 13.24–27.24 pts | Stated by Mission Lane | October 6, 2026 |
| AARP® Essential Rewards Mastercard® from Barclays Barclays | 20.49%–29.99% | 7.00% | 13.49–22.99 pts | Stated by Barclays | October 5, 2026 |
| AARP® Travel Rewards Mastercard® from Barclays Barclays | 20.49%–29.99% | 7.00% | 13.49–22.99 pts | Stated by Barclays | October 5, 2026 |
| Key Cashback® Credit Card KeyBank | 20.74%–27.74% | 7.00% | 13.74–20.74 pts | APR minus prime that day | October 6, 2026 |
| GM Rewards™ Mastercard® Barclays | 22.49%–32.49% | 7.00% | 15.49–25.49 pts | Stated by Barclays | October 5, 2026 |
| opensky® Secured Visa® Credit Card opensky | 23.89% | 6.75% | 17.14 pts | Stated by opensky | October 6, 2026 |
| PNC Secured Visa® Credit Card PNC Bank | 25.74% | 7.00% | 18.74 pts | APR minus prime that day | October 22, 2026 |
| TD Cash Secured Credit Card TD Bank | 26.49% | 6.75% | 19.74 pts | Stated by TD Bank | October 6, 2026 |
| Regions Explore Visa® Credit Card Regions Bank | 26.74% | 7.00% | 19.74 pts | Stated by Regions Bank | October 6, 2026 |
| Key Secured Credit Card® KeyBank | 26.74% | 7.00% | 19.74 pts | APR minus prime that day | October 6, 2026 |
| Huntington® Secured Credit Card Huntington Bank | 26.74% | 7.00% | 19.74 pts | Stated by Huntington Bank | October 6, 2026 |
| Bilt Blue Card Column N.A. | 26.74%–34.74% | 6.75% | 19.99–27.99 pts | Stated by Column N.A. | October 6, 2026 |
| Bilt Obsidian Card Column N.A. | 26.74%–34.74% | 6.75% | 19.99–27.99 pts | Stated by Column N.A. | October 6, 2026 |
| Bilt Palladium Card Column N.A. | 26.74%–34.74% | 6.75% | 19.99–27.99 pts | Stated by Column N.A. | October 6, 2026 |
| Truist Enjoy Cash Secured Credit Card Truist | 26.99% | 7.00% | 19.99 pts | Stated by Truist | October 22, 2026 |
| U.S. Bank Secured Visa® Card U.S. Bank | 27.74% | 7.00% | 20.74 pts | APR minus prime that day | October 5, 2026 |
| Citizens Amp® Mastercard® Citizens | 27.49% | 6.75% | 20.74 pts | Stated by Citizens | October 6, 2026 |
| opensky® Launch Secured Visa® Credit Card opensky | 28.24% | 6.75% | 21.49 pts | Stated by opensky | October 6, 2026 |
| opensky® Plus Secured Visa® Credit Card opensky | 28.24% | 6.75% | 21.49 pts | Stated by opensky | October 6, 2026 |
| U.S. Bank Cash+® Secured Visa® Card U.S. Bank | 28.74% | 7.00% | 21.74 pts | APR minus prime that day | October 5, 2026 |
| U.S. Bank Altitude® Go Secured Visa® Card U.S. Bank | 28.74% | 7.00% | 21.74 pts | APR minus prime that day | October 5, 2026 |
| Slate Edge® Credit Card Chase | 29.24% | 7.00% | 22.24 pts | Stated by Chase | October 6, 2026 |
| Capital One QuicksilverOne Cash Rewards Credit Card Capital One | 29.24% | 7.00% | 22.24 pts | Stated by Capital One | October 6, 2026 |
| Credit One Bank Platinum Visa® for Rebuilding Credit Credit One Bank | 29.74% | 7.00% | 22.74 pts | APR minus prime that day | October 6, 2026 |
| Credit One Bank American Express® for Rebuilding Credit Credit One Bank | 29.74% | 7.00% | 22.74 pts | APR minus prime that day | October 6, 2026 |
| Credit One Bank Secured Card Credit One Bank | 29.74% | 7.00% | 22.74 pts | APR minus prime that day | October 6, 2026 |
| Credit One Bank Platinum Rewards Visa® with No Annual Fee Credit One Bank | 29.74% | 7.00% | 22.74 pts | APR minus prime that day | October 6, 2026 |
| Credit One Bank Platinum Rewards Visa® Card Credit One Bank | 29.74% | 7.00% | 22.74 pts | APR minus prime that day | October 6, 2026 |
| Credit One Bank Platinum X5 Visa Signature® Card Credit One Bank | 29.74% | 7.00% | 22.74 pts | APR minus prime that day | October 6, 2026 |
| Credit One Bank Wander® American Express® Card Credit One Bank | 29.74% | 7.00% | 22.74 pts | APR minus prime that day | October 6, 2026 |
| Credit One Bank Premier American Express® Card Credit One Bank | 29.74% | 7.00% | 22.74 pts | APR minus prime that day | October 6, 2026 |
| Credit One Bank Omni Rewards American Express® Card Credit One Bank | 29.74% | 7.00% | 22.74 pts | APR minus prime that day | October 6, 2026 |
Where an issuer states no margin and its page hadn’t caught up with a change in the prime rate when we checked it, the margin here is off by that change. Where an APR is capped (18% at federal credit unions, for example), the margin shown at the top is what the cap allows, not the margin the issuer states. Cards with a fixed APR, or terms that don’t mention the prime rate, aren’t included. Download every card as a CSV file.
What changed in the latest reading?
The Federal Reserve’s August 2026 card rate survey put the average APR on accounts charged interest at 22.36%, up 0.21 percentage points on May 2026. The prime rate averaged 6.75% that month (unchanged), so the margin over prime is 15.61 percentage points, up 0.21 percentage points. The next reading is for the next survey month, published in the Federal Reserve’s G.19 release about five weeks after the month ends.
Is the credit card margin at a record high?
Yes: at 15.61 percentage points over prime in August 2026, the margin is the highest in the Federal Reserve’s data. In February 2024 the CFPB reported that “APR margin for revolving accounts is now at 14.3 percent, the highest point in recent history” (CFPB, checked October 14, 2026). The same measure from the Federal Reserve’s published series gives 14.27 percentage points for August 2023, so the two agree, and the margin has risen since.
| Figure | Period | Margin over prime | Source |
|---|---|---|---|
| CFPB, revolving accounts | 2023 | 14.3% | CFPB, February 2024 |
| Federal Reserve data, accounts charged interest | August 2023 | 14.27 points | Our calculation, G.19 and H.15 |
| Federal Reserve data, latest | August 2026 | 15.61 points | Our calculation, G.19 and H.15 |
What does the wider margin cost a cardholder?
On a $5,000 balance carried for a year, the average APR of 22.36% costs about $1,118 in interest. With today’s prime rate and the margin of August 2016 (10.26 percentage points), the APR would be 17.01% and the interest about $851: $267 a year less. This is our illustration: simple interest on a constant balance, ignoring compounding, fees and payments.
The CFPB found that major issuers earned an “estimated $25 billion in additional interest revenue by raising APR margin”, and that “excess APR margin may have cost the average cardholder over $250” in 2023.
How we calculate the margin
- Card APR: the Federal Reserve’s average interest rate on credit card accounts assessed interest, from its survey of commercial banks, weighted by the balances charged interest. It is reported for February, May, August and November.
- Prime rate: the bank prime loan rate, the benchmark most card APRs are set from (“prime plus” a margin). We use its monthly average for the same month.
- Fed funds rate: the effective federal funds rate, the overnight rate the Federal Reserve targets, as a monthly average.
- Margin: the card APR minus each rate in the same month, in percentage points. The margin pays for losses, operating costs and rewards as well as profit, so it is not a measure of profit by itself.
- Updates: an automated job downloads the three series from FRED every week and saves a new copy only when the data changes; this page and the download update with it.
For all of the Federal Reserve’s card figures, including balances and late payments, see our credit card statistics, for what the margin costs where you live, the margin’s cost in each state, and for how far every card sits above the proposed 10% cap, the 10% rate cap test.
Use this data
Download every month as a CSV file, with the inputs and both margins. The margins are our calculation, free to use with credit under CC BY 4.0; the Federal Reserve’s own series are in the public domain.
Cite this page
BestCreditCards, “Credit card interest margin,” updated October 14, 2026, https://bestcredit.cards/credit-card-interest-margin. Calculated from Federal Reserve G.19 and H.15 data.Embed the chart
The chart image carries its source. Copy this onto your page:
<a href="https://bestcredit.cards/credit-card-interest-margin"><img src="https://bestcredit.cards/credit-card-interest-margin/chart.png" width="1200" height="630" alt="Credit card interest margin: the average card APR minus the prime rate and the Fed funds rate, November 1994 to August 2026"></a>
<p>Source: <a href="https://bestcredit.cards/credit-card-interest-margin">BestCreditCards</a>, from Federal Reserve data.</p>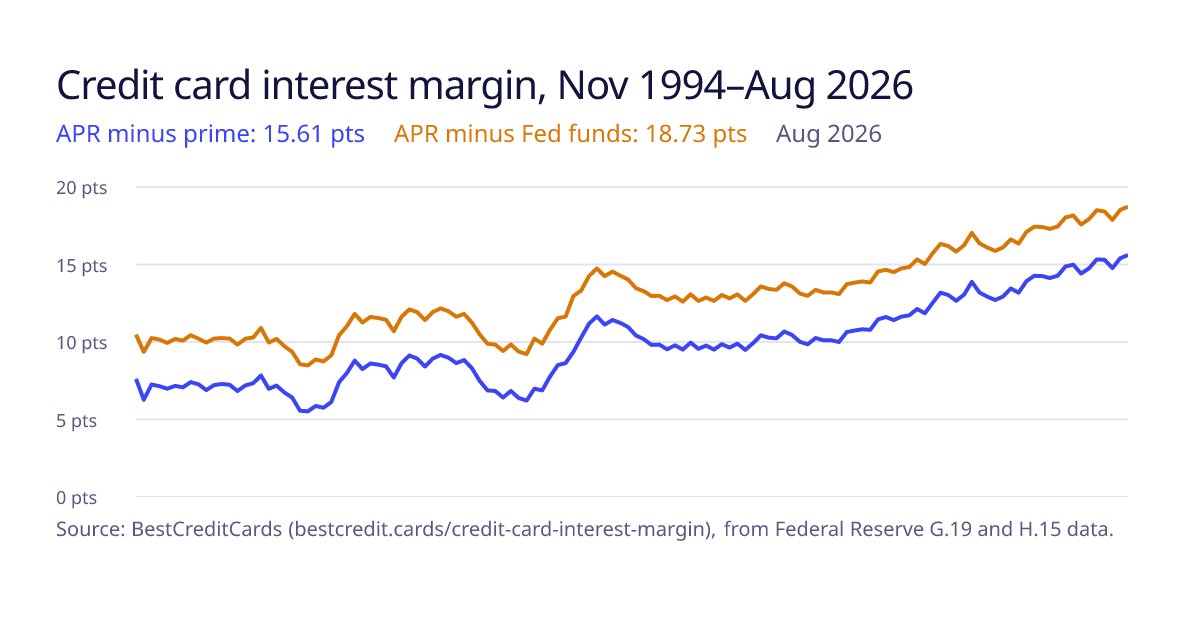
Approved for publication by Matt Woodley on October 14, 2026. Data last changed October 14, 2026. The Federal Reserve series are re-downloaded weekly; the CFPB’s figures are quoted from a saved copy and checked automatically. How we check every figure