Best credit cards, ranked by what they’re worth to you
The best credit card for you depends on what you spend, your credit history and whether you pay in full. Enter roughly what you spend and see which card is worth most to you each year, after fees, with the catch shown before you apply. We rank the 80 cards whose fee and rewards we can put in dollars, out of the 141 US cards we’ve researched. Rates and fees come from issuer pages checked between October 4, 2026 and October 22, 2026. These are dated observations; check the issuer’s current terms before applying.
What do you need a card for?
Ranked only by what each card is worth to you. We currently earn nothing from any card on this site; if that changes, commission will never change the order. How we get paid
- 1
 3.7Best Score 3.7 out of 5
Citizens Summit® World Mastercard®
Citizens · Mastercard
Worth to you each year$498$498 rewards − $0 fee- Rewards
- 3% on dining, groceries; 1.5% on everything else
- Intro offer
- 0% intro APR on balance transfers for 12 months, then 17.49%–27.49% variable APR (The first 12 billing cycles from account opening)
- APR
- 17.49%–27.49% variable APR
- Annual fee
- $0
The catchEverything outside dining and groceries earns 1.5%, so against a flat 2% card you need more than $5,000 a year at restaurants and grocery stores for every $10,000 you spend elsewhere just to break even.
Not forAnyone whose dining and grocery spending is less than half their other spending (a flat 2% card then earns more), or who spends abroad without a Citizens Quest or Private relationship, because of the 3% foreign transaction fee.
Apply on the issuer’s site We don’t earn from this card.How we scored it
How the Best Score of 3.7 is worked out: each part scores 0 to 5 and counts by its weight Part Weight Points Why Value 40% 4.8 Its yearly value after fees as a share of the best of the 80 cards we could value, averaged over 9 example spending profiles. Fees 25% 2.5 Annual fee $0; foreign transaction fee 3%. Interest rate 15% 3.4 Middle of its APR range (17.49%–27.49%): 22.49%. Intro offer 10% 2.9 0% intro APR for 12 months. Transparency 10% 3.6 The issuer’s pages state 8 of the 11 terms we record. Our rating, from the issuer’s published terms only. How the Best Score works
How we worked this out
Your yearly spending and what this card earns on it Category You spend a year You earn Groceries $5,820 $175 Dining $3,276 $98 Gas $2,640 $40 Other travel $876 $13 Drugstores $576 $9 Entertainment $540 $8 Everything else $10,404 $156 - Annual fee: $0
- APR: 17.49%–27.49% variable APR
- 0% intro APR on balance transfers for 12 months, then 17.49%–27.49% variable APR (The first 12 billing cycles from account opening)
- Annual fee checked against the issuer’s rates and fees table (schumer box) on October 6, 2026
- All source checks for this card: October 6, 2026.
- Card image from Citizens, taken from its own page on October 7, 2026
- You pay your full balance every month, so no interest is charged.
- Walmart and select superstores don’t count as grocery stores.
- The 3% foreign transaction fee is waived only with a Citizens Quest Checking, Private Client Checking or Private Bank relationship.
- Not counted: Lyft, Instacart and Mastercard transit credits, which depend on separate offers.
- 2
 3.3Best Score 3.3 out of 5
Blue Cash Preferred® Card from American Express
American Express
Worth to you each year$490$585 rewards − $95 fee · $585 in year one- Rewards
- 6% (up to $6,000 a year) on groceries; 6% on streaming; 3% on transit, gas; 1% on everything else
- Intro offer
- Not published
- APR
- Not published
- Annual fee
- $0 the first year, then $95
The catchFrom the second year it costs $95, and the 6% grocery rate drops to 1% after $6,000 a year.
Not forAnyone who spends little at U.S. supermarkets, because the $95 fee from year two can outweigh the extra cash back, and anyone who spends abroad (2.7% foreign transaction fee).
Apply on the issuer’s site We don’t earn from this card.How we scored it
How the Best Score of 3.3 is worked out: each part scores 0 to 5 and counts by its weight Part Weight Points Why Value 40% 4.3 Its yearly value after fees as a share of the best of the 80 cards we could value, averaged over 9 example spending profiles. Fees 25% 2.2 Annual fee $95; foreign transaction fee 2.7%. Interest rate 15% Not counted APR not published on the page we checked, so not counted. Intro offer 10% Not counted Intro offer not published on the page we checked, so not counted. Transparency 10% 1.8 The issuer’s pages state 4 of the 11 terms we record. Our rating, from the issuer’s published terms only. How the Best Score works
How we worked this out
Your yearly spending and what this card earns on it Category You spend a year You earn Groceries $5,820 $349 Dining $3,276 $33 Gas $2,640 $79 Other travel $876 $9 Drugstores $576 $6 Entertainment $540 $5 Everything else $10,404 $104 - Annual fee: $95
- APR: not published on the page we checked
- Annual fee checked against the issuer’s product page on October 4, 2026
- All source checks for this card: October 4, 2026–October 14, 2026.
- Card image from American Express, taken from its own page on October 4, 2026
- You pay your full balance every month, so no interest is charged.
- The 6% grocery rate applies only at U.S. supermarkets, on up to $6,000 a year, then 1%.
- Only select U.S. streaming subscriptions earn 6%. The calculator counts all your streaming spending at 6%, so check yours are on American Express’s list.
- The up to $120 a year Disney streaming credit is not counted: it depends on which subscriptions you pay for.
- Cash back comes as Reward Dollars, redeemed as a statement credit.
- The annual fee is lower in the first year, so year-one value includes the difference. The ranking uses the fee you pay from year two.
- 3
 3.7Best Score 3.7 out of 5
Citi Double Cash® Card
Citi · Mastercard
Worth to you each year$483$483 rewards − $0 fee · $683 in year one- Rewards
- 2% on everything
- Intro offer
- 0% intro APR on balance transfers for 18 months, then 18.49%–28.74% variable APR (Balance transfers completed within 4 months of account opening)
- APR
- 18.49%–28.74% variable APR
- Annual fee
- $0
The catchA 3% fee on foreign purchases, and the intro 0% applies only to balance transfers, which cost 3% (at least $5) in the first 4 months and 5% after.
Not forAnyone who spends abroad, because of the 3% foreign purchase fee, or who carries a balance on new purchases: the 0% intro rate covers balance transfers only.
Apply on the issuer’s site We don’t earn from this card.How we scored it
How the Best Score of 3.7 is worked out: each part scores 0 to 5 and counts by its weight Part Weight Points Why Value 40% 4.5 Its yearly value after fees as a share of the best of the 80 cards we could value, averaged over 9 example spending profiles. Fees 25% 2.5 Annual fee $0; foreign transaction fee 3%. Interest rate 15% 3.0 Middle of its APR range (18.49%–28.74%): 23.62%. Intro offer 10% 4.3 0% intro APR for 18 months. Transparency 10% 4.1 The issuer’s pages state 9 of the 11 terms we record. Our rating, from the issuer’s published terms only. How the Best Score works
How we worked this out
Your yearly spending and what this card earns on it Category You spend a year You earn Groceries $5,820 $116 Dining $3,276 $66 Gas $2,640 $53 Other travel $876 $18 Drugstores $576 $12 Entertainment $540 $11 Everything else $10,404 $208 - Annual fee: $0
- APR: 18.49%–28.74% variable APR
- 0% intro APR on balance transfers for 18 months, then 18.49%–28.74% variable APR (Balance transfers completed within 4 months of account opening)
- Annual fee checked against the issuer’s product page, including its pricing details on October 5, 2026
- All source checks for this card: October 5, 2026.
- Card image from Citi, taken from its own page on October 6, 2026
- You pay your full balance every month, so no interest is charged.
- Citi pays the 2% as ThankYou points: 1 point per $1 when you buy and 1 more per $1 when you pay. Citi says 10,000 points redeem for $100 in cash, so they are counted at that rate; the second 1% depends on paying for the purchase.
- Not counted: the extra 3% on hotels, car rentals and attractions booked through Citi Travel.
- Balance transfers earn no cash back.
- Welcome bonus counted because your spending meets the requirement within 6 months.
- 4
 4.0Best Score 4.0 out of 5
Credit One Bank Omni Rewards American Express® Card
Credit One Bank · American Express
Worth to you each year$483$483 rewards − $0 fee · $683 in year one- Rewards
- 2% on everything
- Intro offer
- Not published
- APR
- 29.74% variable APR
- Annual fee
- $0
The catchCredit One recommends it only for excellent credit, yet its APR is 29.74% variable, and the minimum credit line is $5,000.
Not forAnyone with fair or limited credit (Credit One recommends it for excellent credit), and anyone who carries a balance: a 29.74% variable APR is high for a card aimed at excellent credit.
Apply on the issuer’s site We don’t earn from this card.How we scored it
How the Best Score of 4.0 is worked out: each part scores 0 to 5 and counts by its weight Part Weight Points Why Value 40% 4.5 Its yearly value after fees as a share of the best of the 80 cards we could value, averaged over 9 example spending profiles. Fees 25% 5.0 Annual fee $0; foreign transaction fee 0%. Interest rate 15% 0.8 APR 29.74%. Intro offer 10% Not counted Intro offer not published on the page we checked, so not counted. Transparency 10% 4.1 The issuer’s pages state 9 of the 11 terms we record. Our rating, from the issuer’s published terms only. How the Best Score works
How we worked this out
Your yearly spending and what this card earns on it Category You spend a year You earn Groceries $5,820 $116 Dining $3,276 $66 Gas $2,640 $53 Other travel $876 $18 Drugstores $576 $12 Entertainment $540 $11 Everything else $10,404 $208 - Annual fee: $0
- APR: 29.74% variable APR
- Annual fee checked against the issuer’s terms, fees & conditions (schumer box, eligibility criteria and rewards program terms) on October 6, 2026
- All source checks for this card: October 6, 2026.
- Card image from Credit One Bank, taken from its own page on October 6, 2026
- You pay your full balance every month, so no interest is charged.
- Credit One says cash back rewards are redeemed for statement credits, gift cards or other goods and services, and “have no cash value” until redeemed; the terms we saved give no minimum redemption.
- Welcome bonus counted because your spending meets the requirement within 6 months.
- 5
 4.3Best Score 4.3 out of 5
Fifth Third Preferred Cash/Back Card
Fifth Third Bank · Mastercard
Worth to you each year$483$483 rewards − $0 fee- Rewards
- 2% on everything
- Intro offer
- Not published
- APR
- 19.24%–29.24% variable APR
- Annual fee
- $0
The catchYou must be a Fifth Third Preferred Banking customer, and the page we saved doesn’t state what that takes or whether the card has an intro rate.
Not forAnyone who isn’t a Fifth Third Preferred Banking customer: the card is only for them, and the page we saved doesn’t say what Preferred Banking requires.
Apply on the issuer’s site We don’t earn from this card.How we scored it
How the Best Score of 4.3 is worked out: each part scores 0 to 5 and counts by its weight Part Weight Points Why Value 40% 4.5 Its yearly value after fees as a share of the best of the 80 cards we could value, averaged over 9 example spending profiles. Fees 25% 5.0 Annual fee $0; foreign transaction fee 0%. Interest rate 15% 2.8 Middle of its APR range (19.24%–29.24%): 24.24%. Intro offer 10% Not counted Intro offer not published on the page we checked, so not counted. Transparency 10% 3.6 The issuer’s pages state 8 of the 11 terms we record. Our rating, from the issuer’s published terms only. How the Best Score works
How we worked this out
Your yearly spending and what this card earns on it Category You spend a year You earn Groceries $5,820 $116 Dining $3,276 $66 Gas $2,640 $53 Other travel $876 $18 Drugstores $576 $12 Entertainment $540 $11 Everything else $10,404 $208 - Annual fee: $0
- APR: 19.24%–29.24% variable APR
- Annual fee checked against the issuer’s product page: notices & disclosures (rates and fees) on October 6, 2026
- All source checks for this card: October 6, 2026.
- Card image from Fifth Third Bank, taken from its own page on October 6, 2026
- You pay your full balance every month, so no interest is charged.
- Not counted: Lyft, Peacock and Instacart credits, which depend on separate Mastercard offers.
61 cards aren’t ranked, and why
A card isn’t ranked when our record lacks a figure the calculation needs; we never count a missing figure as zero. The reason for each card
Rewards published, but no cash value we can use (39)
Wells Fargo Autograph Journey℠ Card; Citi Strata® Card; Citi Strata Premier® Card; Citi Strata Elite® Card; U.S. Bank Shield® Visa® Card; U.S. Bank Altitude® Connect Visa Signature® Card; U.S. Bank Altitude® Go Visa Signature® Card; U.S. Bank Altitude® Go Secured Visa® Card; JetBlue Card; JetBlue Plus Card; Wyndham Rewards Earner® Card; Wyndham Rewards Earner® Plus Card; GM Rewards™ Mastercard®; Frontier Airlines World Mastercard®; United℠ Explorer Card; Southwest Rapid Rewards® Plus Credit Card; Marriott Bonvoy Boundless® Credit Card; IHG One Rewards Premier Credit Card; American Express® Gold Card; The Platinum Card® from American Express; Delta SkyMiles® Gold American Express Card; Delta SkyMiles® Blue American Express Card; Hilton Honors American Express Card; Hilton Honors American Express Surpass® Card; Marriott Bonvoy Bevy® American Express® Card; Capital One Venture Rewards Credit Card; Capital One VentureOne Rewards Credit Card; Capital One Venture X Rewards Credit Card; BankAmericard® Credit Card; Wells Fargo Reflect® Card; PenFed Platinum Rewards Visa Signature® Card; PenFed Pathfinder Rewards® Visa Signature® Card; Bilt Blue Card; Bilt Obsidian Card; Bilt Palladium Card; Verizon Visa® Card; opensky® Launch Secured Visa® Credit Card; opensky® Secured Visa® Credit Card; opensky® Plus Secured Visa® Credit Card
No rewards described on the pages we checked (19)
Capital One Platinum Secured Credit Card; Capital One Platinum Credit Card; U.S. Bank Secured Visa® Card; Slate Edge® Credit Card; PNC Spend Wise® Visa® Credit Card; PNC Secured Visa® Credit Card; TD FlexPay Credit Card; Navy Federal Platinum Credit Card; PenFed Gold Visa® Card; Truist Future Credit Card; Citizens Spring® World Mastercard®; Citizens Amp® Mastercard®; Fifth Third Truly Simple® Credit Card; Fifth Third Secured Credit Card; Regions Life Visa® Credit Card; Regions Explore Visa® Credit Card; KeyBank Latitude® Credit Card; Key Secured Credit Card®; Alliant Visa® Platinum Credit Card
Annual fee varies by applicant or isn’t published (3)
Mission Lane Green Line Visa®; Mission Lane Secured Visa®; Avant Credit Card (AvantCard)
We currently earn nothing from any card on this site. If that changes, commission will never change the order, and we’ll say so at every link. How we get paid
What is a credit card worth to a real US household?
We took the average card spending of each fifth of US households by income, from the BLS Consumer Expenditure Survey for 2024, and ran it through all 80 cards we can value. A household in the middle fifth spends about $2,011 a month on things people usually pay for by card. What holds across the incomes:
- The same card leads at every income: the Citizens Summit® World Mastercard®. The best card that pays one flat rate on everything comes within $9 to $16 a year of the leader.
- No card with an annual fee beats the best no-fee card, at any income. That holds for all 15 fee cards we can value, from the lowest fifth ($1,135 a month) to the highest ($4,103). To come out ahead, a fee card has to be worth the difference to you in perks or points we don’t count.
- Carry more than a few thousand dollars and no card’s rewards cover the interest. At the middle of each card’s published APR range, the most any card can carry before a year’s interest outweighs its rewards is $1,694 for the lowest fifth and $6,123 for the highest.
| Household income before tax | Card spending a month | Card worth most a year | Lead over the best flat-rate card | Best fee card vs best no-fee card | Largest balance rewards still cover |
|---|---|---|---|---|---|
| Lowest 20% of incomes under $29,932 | $1,135 | $287 Citizens Summit® World Mastercard® | $14 over 9 tied flat-rate cards at $272 | $258 vs $287 Blue Cash Preferred® Card from American Express | $1,694 Navy Federal cashRewards Plus Credit Card |
| Second 20% $29,932 to $57,451 | $1,589 | $397 Citizens Summit® World Mastercard® | $16 over 9 tied flat-rate cards at $381 | $384 vs $397 Blue Cash Preferred® Card from American Express | $2,371 Navy Federal cashRewards Plus Credit Card |
| Middle 20% of incomes $57,452 to $94,510 | $2,011 | $498 Citizens Summit® World Mastercard® | $16 over 9 tied flat-rate cards at $483 | $490 vs $498 Blue Cash Preferred® Card from American Express | $3,001 Navy Federal cashRewards Plus Credit Card |
| Fourth 20% $94,511 to $155,924 | $2,694 | $663 Citizens Summit® World Mastercard® | $16 over 9 tied flat-rate cards at $647 | $599 vs $663 Credit One Bank Wander® American Express® Card | $4,020 Navy Federal cashRewards Plus Credit Card |
| Highest 20% of incomes $155,925 or more | $4,103 | $993 Citizens Summit® World Mastercard® | $9 over 9 tied flat-rate cards at $985 | $965 vs $993 Credit One Bank Wander® American Express® Card | $6,123 Navy Federal cashRewards Plus Credit Card |
Download this table (CSV), free to use with credit under CC BY 4.0.
How we turned the survey into card spending
The survey reports what households spend, by item, as an average for each fifth of incomes. We turn it into a month and count only spending people usually put on a card:
- Groceries: Food at home
- Dining: Food away from home
- Gas: Gasoline and other fuels
- Other travel: Public and other transportation
- Drugstores: Drugs
- Entertainment: Fees and admissions
- Everything else: Alcoholic beverages; Telephone services; Housekeeping supplies; Household furnishings and equipment; Apparel and services; Maintenance and repairs; Audio and visual equipment and services; Pets, toys, hobbies, and playground equipment; Other entertainment supplies, equipment, and services; Personal care products and services; Reading
Left out: Shelter; Utilities, fuels, and public services; Household operations; Vehicle purchases (net outlay); Vehicle finance charges; Vehicle insurance; Vehicle rental, leases, licenses, and other charges; Health insurance; Medical services; Medical supplies; Education; Tobacco products and smoking supplies; Miscellaneous; Cash contributions; Personal insurance and pensions. Flights and hotels aren’t separate in this table, so they count as other travel or not at all; streaming and online shopping are recorded by item, not by where you buy, so they count under the item.
These are averages (means), which large spenders pull up, not a typical household. Values are rewards minus the annual fee, every year after the first, for paying in full; the balance column uses the middle of each card’s published APR range and simple interest. Card terms are from our approved records, checked automatically against each issuer’s saved terms.
Source: Bureau of Labor Statistics, Table 1101. Quintiles of income before taxes: Annual expenditure means, shares, standard errors, and relative standard errors, Consumer Expenditure Surveys, 2024 (retrieved October 27, 2026; data file). Our calculation.
Is a card with an annual fee worth it?
Only if its credits and perks are worth more to you than the gap below. Our values count rewards and the fee, not travel credits, lounge access or insurance (what our values leave out), so for each fee card we can value, the table shows what those extras would have to be worth a year for the card just to match the best no-fee card, on each income group’s real spending. For a middle-income household, the perks must be worth from $8 for the Blue Cash Preferred® Card from American Express to $987 for the Chase Sapphire Reserve® Credit Card, which charges $795 a year.
| Card | Annual fee | Middle-income household | Range across incomes |
|---|---|---|---|
| Blue Cash Preferred® Card from American Express | $95 | $8 | $8 to $217 least for the middle 20%, most for the highest 20% |
| Bank of America® Premium Rewards® Credit Card | $95 | $211 | $167 to $299 least for the lowest 20%, most for the highest 20% |
| Chase Sapphire Preferred® Credit Card | $95 | $225 | $183 to $338 least for the lowest 20%, most for the highest 20% |
| Breeze Easy® Visa® Credit Card | $89 | $255 | $185 to $420 least for the lowest 20%, most for the highest 20% |
| Navy Federal Flagship Premier Visa Signature® Credit Card | $95 | $260 | $198 to $365 least for the lowest 20%, most for the highest 20% |
| TD First Class℠ Visa Signature® Credit Card | $89 | $263 | $197 to $385 least for the lowest 20%, most for the highest 20% |
| Chase Sapphire Reserve® Credit Card | $795 | $987 | $912 to $1,143 least for the lowest 20%, most for the highest 20% |
| Credit One Bank Wander® American Express® Card For building credit: chosen for approval, not rewards | $95 | $80 | $29 to $110 least for the highest 20%, most for the lowest 20% |
| Credit One Bank Platinum X5 Visa Signature® Card For building credit: chosen for approval, not rewards | $95 | $152 | $46 to $396 least for the lowest 20%, most for the highest 20% |
| TD Cash Secured Credit Card For building credit: chosen for approval, not rewards | $29 | $162 | $108 to $284 least for the lowest 20%, most for the highest 20% |
| Capital One QuicksilverOne Cash Rewards Credit Card For building credit: chosen for approval, not rewards | $39 | $175 | $121 to $294 least for the lowest 20%, most for the highest 20% |
| Credit One Bank Premier American Express® Card For building credit: chosen for approval, not rewards | $39 | $296 | $190 to $540 least for the lowest 20%, most for the highest 20% |
| Credit One Bank Platinum Rewards Visa® Card For building credit: chosen for approval, not rewards | $39 | $453 | $275 to $900 least for the lowest 20%, most for the highest 20% |
| Credit One Bank American Express® for Rebuilding Credit For building credit: chosen for approval, not rewards | $99 | $513 | $335 to $960 least for the lowest 20%, most for the highest 20% |
| Credit One Bank Platinum Visa® for Rebuilding Credit For building credit: chosen for approval, not rewards | $99 | $513 | $335 to $960 least for the lowest 20%, most for the highest 20% |
Gap = the best no-fee card’s rewards minus its fee, less this card’s, both a year from year two and on the same household’s spending (BLS Consumer Expenditure Survey; see real US households). A card with a lower first-year fee costs less in year one. 24 fee cards aren’t shown because we can’t put their points or miles in dollars, so we can’t say what their perks must be worth: Wells Fargo Autograph Journey℠ Card; Citi Strata Premier® Card; Citi Strata Elite® Card; JetBlue Plus Card; Wyndham Rewards Earner® Plus Card; Frontier Airlines World Mastercard®; United℠ Explorer Card; Southwest Rapid Rewards® Plus Credit Card; Marriott Bonvoy Boundless® Credit Card; IHG One Rewards Premier Credit Card; American Express® Gold Card; The Platinum Card® from American Express; Delta SkyMiles® Gold American Express Card; Hilton Honors American Express Surpass® Card; Marriott Bonvoy Bevy® American Express® Card; Capital One Venture Rewards Credit Card; Capital One Venture X Rewards Credit Card; PenFed Pathfinder Rewards® Visa Signature® Card; Bilt Obsidian Card; Bilt Palladium Card; Fifth Third Secured Credit Card; Regions Explore Visa® Credit Card; opensky® Launch Secured Visa® Credit Card; opensky® Secured Visa® Credit Card.
Who pays for credit card rewards?
Part of the money comes from the merchant. Every card purchase carries a swipe fee, called interchange, which Visa’s schedule says is paid to the cardholder’s bank. On the middle-income household’s card spending, Visa’s published rates come to at least $376 a year on a card with no rewards and $519 on a premium Visa Infinite card, before the cents charged on each purchase. The card worth most to that household in our records returns $498 a year. Merchants pay more when you use a premium card. Interest from people who carry a balance is another source: see how far card APRs sit above the prime rate in our credit card interest margin study.
| Household | Swipe fees: All other (no rewards) | Swipe fees: Traditional Rewards | Swipe fees: Visa Infinite (premium) | Best card returns |
|---|---|---|---|---|
| Lowest 20% of incomes $1,135 a month on cards | $212 | $222 | $293 | $287 |
| Second 20% $1,589 a month on cards | $296 | $309 | $409 | $397 |
| Middle 20% of incomes $2,011 a month on cards | $376 | $394 | $519 | $498 |
| Fourth 20% $2,694 a month on cards | $506 | $531 | $701 | $663 |
| Highest 20% of incomes $4,103 a month on cards | $780 | $821 | $1,089 | $993 |
What researchers disagree about. Federal Reserve Board economists estimated in January 2023 that rewards cards move money between households: “We estimate an aggregate annual redistribution of $15 billion from less to more educated, poorer to richer, and high to low minority areas, widening existing disparities.” They also found that “banks incentivize the use of reward cards by offering lower interest rates than on comparable cards without rewards.” An industry-funded reanalysis of earlier Boston Fed work reached the opposite view, that “the POS cross-subsidies are found to be small, non-existent, or reversed.” These are the researchers’ conclusions, not ours.
The rates we used, and the limits
- Supermarket Credit—All Other: All other (no rewards) 1.50%; Traditional Rewards 1.50%; Visa Infinite (premium) 2.00%
- Restaurant 2: All other (no rewards) 2.10%; Traditional Rewards 2.10%; Visa Infinite (premium) 2.60%
- Fuel: All other (no rewards) 1.15%; Traditional Rewards 1.15%; Visa Infinite (premium) 1.15%
- Travel 2: All other (no rewards) 1.75%; Traditional Rewards 1.95%; Visa Infinite (premium) 2.55%
- Product 2: All other (no rewards) 1.51%; Traditional Rewards 1.65%; Visa Infinite (premium) 2.30%
Groceries use the supermarket rate, dining the restaurant rate, gas the fuel rate, travel the travel rate, and everything else the standard retail rate. The largest supermarkets and retailers qualify for lower tiered rates, and we leave out the fixed cents per purchase, so these are rough floors for a Visa card. Mastercard, American Express and Discover set their own rates; the best card for these households is on Mastercard, so Visa’s schedule is a published benchmark, not any one card’s exact fee.
Sources: Visa, Visa USA Interchange Reimbursement Fees, rates effective October 24, 2026 (retrieved October 27, 2026); Who Pays For Your Rewards? Redistribution in the Credit Card Market, Federal Reserve Board staff (Agarwal, Presbitero, Silva and Wix), FEDS 2023-007, January 2023; A Reexamination of Who Gains and Who Loses from Credit Card Payments, Policy and Economic Research Council (PERC), March 2013, a reanalysis of the Boston Fed staff studies. Household spending: BLS Consumer Expenditure Survey (see above). Our calculation.
Best credit cards for what you need
Each need below names its pick, ranked only by what the card is worth after fees on a stated example. The examples differ by need, so compare a pick with the calculator above rather than across sections. The dollar values are calculations; eligibility and category terms are issuer facts from dated sources; each catch and who a card doesn’t suit are our editorial judgments. A high calculated value does not mean you qualify. Or try Cardnivo, our credit card finder: matches for your credit and goals, with no credit check.
How we test when a different card wins. The sections for groceries, gas, dining and travel each test when a different card leads. Each compares that need’s list with every approved card that pays one uncapped rate on all purchases, so a flat-rate card can win even though it isn’t on the category list. Values are annual rewards minus the ongoing annual fee, paying in full; eligibility, interest, welcome offers and perks don’t affect the order. A card missing a fee or reward figure isn’t ranked, and a missing value is never counted as zero. A tie means equal annual values to the cent. The spending ranges come from testing every whole-dollar monthly amount in the category with the rest of the example held fixed, both ends included: they are tested ranges, not exact break-even points or predictions above the highest amount tested. These tests stay on each need’s stated example when you change the calculator, and they cover our recorded rewards, not every US card or way to redeem. Calculation limits.
Compare our best credit card picks by need
Each pick below leads its list on a stated example. Compare fees, rates and restrictions here, then follow a need to its section for the ranking, the catch and whether a fee pays for itself.
| Need and card | Annual fee | Purchase APR | Example value after fee | The catch and eligibility |
|---|---|---|---|---|
| Best cash back credit cardsCitizens Summit® World Mastercard® | $0 | 17.49%–27.49% variable APR | $342 a year On $1,400 a month of everyday household spending. Bonuses and interest excluded. | Everything outside dining and groceries earns 1.5%, so against a flat 2% card you need more than $5,000 a year at restaurants and grocery stores for every $10,000 you spend elsewhere just to break even. Who can apply and when we checkedEligibility not published on the pages checked. Not for: Anyone whose dining and grocery spending is less than half their other spending (a flat 2% card then earns more), or who spends abroad without a Citizens Quest or Private relationship, because of the 3% foreign transaction fee. Source checks: Oct 6, 2026. Issuer’s rate terms. |
Best first credit cards: for students Capital One Savor Student Cash Rewards Credit Card | $0 | 18.74%–28.74% variable APR | $173 a year On $700 a month of first-card spending. Bonuses and interest excluded. | Only 1% on everything outside its 3% categories, and the balance transfer fee isn’t on the product page. Who can apply and when we checkedStudents enrolled, or admitted and enrolling within three months, at an accredited university, community college or other higher education institution Not for: Anyone who isn’t in higher education: the issuer offers it to students. Source checks: Oct 14, 2026–Oct 22, 2026. Issuer’s rate terms. |
Best first credit cards: with no deposit Chase Freedom Rise® Credit Card | $0 | 18.49%–27.99% variable APR | $126 a year On $700 a month of first-card spending. Bonuses and interest excluded. | Chase says approval is more likely with at least $250 in a Chase account, and its foreign transaction fee isn’t on the product page. Who can apply and when we checkedAimed at people new to credit and students; Chase says having at least $250 in a Chase checking or savings account increases the chance of approval Not for: Anyone without a Chase bank account who wants the best chance of approval: Chase says a $250 Chase balance helps. Source checks: Oct 4, 2026–Oct 14, 2026. Issuer’s rate terms. |
Best first credit cards: if you can put down a deposit Truist Enjoy Cash Secured Credit Card | $0 | 26.99% variable APR | $130 a year On $700 a month of first-card spending. Bonuses and interest excluded. | Your credit limit equals the deposit you lock in a Truist savings account, Truist names no route to an unsecured card on these pages, and the bonus rates add at most $20 a month over 1%. Who can apply and when we checkedAfter conditional approval, you must fund a Truist secured savings account with a deposit equal to the approved credit limit before the card is issued Not for: Anyone who will carry a balance, at 26.99% variable, or who needs to know the minimum deposit up front: the pages we saved don’t state one. Source checks: Oct 6, 2026–Oct 22, 2026. Issuer’s rate terms. |
| Best student credit cardsCapital One Savor Student Cash Rewards Credit Card | $0 | 18.74%–28.74% variable APR | $142 a year On $550 a month of student spending. Bonuses and interest excluded. | The same card as our pick for first credit cards: its catch and eligibility are in that row. |
| Best credit cards for groceriesCitizens Summit® World Mastercard® | $0 | 17.49%–27.49% variable APR | $482 a year On $1,730 a month of grocery-heavy household spending. Bonuses and interest excluded. | The same card as our pick for cash back credit cards: its catch and eligibility are in that row. |
| Best credit cards for gasBlue Cash Preferred® Card from American Express | $0 the first year, then $95 | Not published | $429 a year On $1,470 a month of commuting household spending. Bonuses and interest excluded. | From the second year it costs $95, and the 6% grocery rate drops to 1% after $6,000 a year. Who can apply and when we checkedEligibility not published on the pages checked. Not for: Anyone who spends little at U.S. supermarkets, because the $95 fee from year two can outweigh the extra cash back, and anyone who spends abroad (2.7% foreign transaction fee). Source checks: Oct 4, 2026–Oct 14, 2026. Issuer’s fee terms. |
| Best no annual fee credit cardsCitizens Summit® World Mastercard® | $0 | 17.49%–27.49% variable APR | $342 a year On $1,400 a month of everyday household spending. Bonuses and interest excluded. | The same card as our pick for cash back credit cards: its catch and eligibility are in that row. |
| Best credit cards for diningCitizens Summit® World Mastercard® | $0 | 17.49%–27.49% variable APR | $373 a year On $1,370 a month of dining-heavy spending. Bonuses and interest excluded. | The same card as our pick for cash back credit cards: its catch and eligibility are in that row. |
Best travel credit cards Credit One Bank Wander® American Express® Card | $95 | 29.74% variable APR | $609 a year On $2,070 a month of travel-heavy spending. Bonuses and interest excluded. | The $95 annual fee is billed when the account opens, so a $400 credit line starts with about $305 available, and the 10-point hotel and car rate needs bookings through Credit One’s travel provider. Who can apply and when we checkedAverage to excellent credit, as Credit One recommends it. Credit One says you may not qualify if you already have an open or unpaid Credit One account or a pending application, live in a U.S. territory, have an APO/FPO address, or are covered by the Military Lending Act. Not for: Anyone who spends less than about $2,375 a year on travel, dining and gas: below that, the extra 4 points per dollar don’t cover the $95 fee compared with a no-fee 1% card. Also anyone who carries a balance, at a 29.74% variable APR. Source checks: Oct 6, 2026. Issuer’s rate terms. |
The examples differ, so the annual values cannot be compared as an overall ranking. Pay in full to avoid interest. Our lists cover the cards in our records, not the whole US market. How we choose and calculate.
Compare cards using the same spending profile, or find cards for your credit and goals.
Best cash back credit cards
Among the cash back credit cards in our records, the Citizens Summit® World Mastercard® is worth the most on our example everyday household spending of $1,400 a month: $342 a year after fees.
Our pick for cash back credit cards: Citizens Summit® World Mastercard®
Why it wonThe Citizens Summit® World Mastercard® is worth $342 a year on the example spending ($342 in rewards, $0 annual fee), the most of the 56 cards we could value for this need.
The catchEverything outside dining and groceries earns 1.5%, so against a flat 2% card you need more than $5,000 a year at restaurants and grocery stores for every $10,000 you spend elsewhere just to break even.
Not for: Anyone whose dining and grocery spending is less than half their other spending (a flat 2% card then earns more), or who spends abroad without a Citizens Quest or Private relationship, because of the 3% foreign transaction fee.
If the Citizens Summit® World Mastercard® doesn’t suit you, the next-best of the cash back credit cards on the same everyday household spending is the Citi Double Cash® Card, worth $336 a year after fees ($6 less).
| Card | Worth a year after fees | Annual fee | Rewards | Standard APR | Foreign transaction fee |
|---|---|---|---|---|---|
| 1. Citizens Summit® World Mastercard® | $342 | $0 | 3% on dining, groceries; 1.5% on everything else | 17.49%–27.49% variable APR | 3% |
| 2. Citi Double Cash® Card | $336 | $0 | 2% on everything | 18.49%–28.74% variable APR | 3% |
| 3. Fifth Third Preferred Cash/Back Card | $336 | $0 | 2% on everything | 19.24%–29.24% variable APR | None |
| 4. Navy Federal cashRewards Plus Credit Card | $336 | $0 | 2% on everything | 14.15%–18% variable APR | None |
| 5. PNC Cash Unlimited® Visa Signature® Credit Card | $336 | $0 | 2% on everything | 18.74%–28.74% variable APR | None |
Check eligibility, merchant restrictions and sources for our pick
- Citizens Summit® World Mastercard®
Eligibility: Not established from our sources; check with the issuer.
Annual fee: $0. Rates and Fees Table (Schumer box) (checked 2026-10-06). Rewards source: Product page (checked 2026-10-06).
We include approved cards whose recorded reward rules earn cash back or cash rewards, supported by the issuer’s own words. Cards with no recorded cash rewards, unvalued rewards, or only points earn rules are not ranked here. We model the recorded ongoing rates, not rotating or selected-category bonuses that require activation or a choice. An illustrative spread of everyday spending, not a household survey. The order is annual cash rewards minus the ongoing annual fee; welcome offers, interest, statement credits and other perks do not determine it. Cash rewards may be redeemed as statement credits or through other issuer-specific options; check the terms. 56 cards compared; 12 more considered and left out. How we compare cards
Best first credit cards
The first credit cards worth most on our example first-card spending of $700 a month depend on your situation: for students, the Capital One Savor Student Cash Rewards Credit Card; with no deposit, the Chase Freedom Rise® Credit Card; and if you can put down a deposit, the Truist Enjoy Cash Secured Credit Card.
| Your situation | Our pick | Worth a year after fees | Deposit | The catch |
|---|---|---|---|---|
| You’re a student Cards their issuers offer to students. | Capital One Savor Student Cash Rewards Credit Card | $173 | Not published | Only 1% on everything outside its 3% categories, and the balance transfer fee isn’t on the product page. |
| No credit history, no deposit Cards whose issuers say they take people new to credit, with no deposit. | Chase Freedom Rise® Credit Card | $126 | Not published | Chase says approval is more likely with at least $250 in a Chase account, and its foreign transaction fee isn’t on the product page. |
| You can put down a deposit Secured cards: a refundable deposit opens the account and sets the credit line. | Truist Enjoy Cash Secured Credit Card | $130 | Not published | Your credit limit equals the deposit you lock in a Truist savings account, Truist names no route to an unsecured card on these pages, and the bonus rates add at most $20 a month over 1%. |
| Card | Worth a year after fees | Annual fee | Deposit | Rewards | Standard APR |
|---|---|---|---|---|---|
| 1. Capital One Savor Student Cash Rewards Credit Card | $173 | $0 | Not published | 3% on groceries, dining, entertainment, streaming; 1% on everything else | 18.74%–28.74% variable APR |
| 2. Truist Enjoy Cash Secured Credit Card | $130 | $0 | Not published | 3% on gas, 2% on groceries, 2% on streaming (up to $12,000 a year combined, then 1%); 1% on everything else | 26.99% variable APR |
| 3. Capital One Quicksilver Student Cash Rewards Credit Card | $126 | $0 | Not published | 1.5% on everything | 18.74%–28.74% variable APR |
| 4. Chase Freedom Rise® Credit Card | $126 | $0 | Not published | 1.5% on everything | 18.49%–27.99% variable APR |
| 5. Bank of America® Customized Cash Rewards Secured Credit Card | $108 | $0 | From $200 ($200 minimum, up to $5,000) | 2% (up to $10,000 a year) on groceries; 1% on everything else | 27.74% variable APR |
Check eligibility, merchant restrictions and sources for these picks
- Capital One Savor Student Cash Rewards Credit Card
Eligibility: Students enrolled, or admitted and enrolling within three months, at an accredited university, community college or other higher education institution Product page (checked 2026-10-22).
Annual fee: $0. Product page (checked 2026-10-22). Rewards source: Product page (checked 2026-10-22).
Not for: Anyone who isn’t in higher education: the issuer offers it to students.
- Chase Freedom Rise® Credit Card
Eligibility: Aimed at people new to credit and students; Chase says having at least $250 in a Chase checking or savings account increases the chance of approval Product page (checked 2026-10-04).
Annual fee: $0. Product page (checked 2026-10-04). Rewards source: Product page (checked 2026-10-04).
Not for: Anyone without a Chase bank account who wants the best chance of approval: Chase says a $250 Chase balance helps.
- Truist Enjoy Cash Secured Credit Card
Eligibility: After conditional approval, you must fund a Truist secured savings account with a deposit equal to the approved credit limit before the card is issued Rates, fees & rewards disclosure (Schumer box) (checked 2026-10-22).
Annual fee: $0. Rates, fees & rewards disclosure (Schumer box) (checked 2026-10-22). Rewards source: Product page (checked 2026-10-06).
Not for: Anyone who will carry a balance, at 26.99% variable, or who needs to know the minimum deposit up front: the pages we saved don’t state one.
We include starter cards for beginners: cards whose issuer says, on its own page, that the card is for students, for people new to credit, or for building or rebuilding credit. An example of lighter spending for someone getting their first card. It is illustrative, not a statistic. 27 cards compared, 10 of them not ranked because our record lacks a figure needed for the calculation; 4 more considered and left out. How we compare cards
Best student credit cards
Among the student credit cards in our records, the Capital One Savor Student Cash Rewards Credit Card is worth the most on our example student spending of $550 a month: $142 a year after fees.
Our pick for student credit cards: Capital One Savor Student Cash Rewards Credit Card
Why it wonThe Capital One Savor Student Cash Rewards Credit Card is worth $142 a year on the example spending ($142 in rewards, $0 annual fee), the most of the 6 cards we could value for this need.
The catchOnly 1% on everything outside its 3% categories, and the balance transfer fee isn’t on the product page.
Not for: Anyone who isn’t in higher education: the issuer offers it to students.
If the Capital One Savor Student Cash Rewards Credit Card doesn’t suit you, the next-best of the student credit cards on the same student spending is the Capital One Quicksilver Student Cash Rewards Credit Card, worth $99 a year after fees ($43 less).
| Card | Worth a year after fees | Annual fee | Rewards | Standard APR | Foreign transaction fee |
|---|---|---|---|---|---|
| 1. Capital One Savor Student Cash Rewards Credit Card | $142 | $0 | 3% on groceries, dining, entertainment, streaming; 1% on everything else | 18.74%–28.74% variable APR | None |
| 2. Capital One Quicksilver Student Cash Rewards Credit Card | $99 | $0 | 1.5% on everything | 18.74%–28.74% variable APR | None |
| 3. Chase Freedom Rise® Credit Card | $99 | $0 | 1.5% on everything | 18.49%–27.99% variable APR | Not published |
| 4. Discover it® Student Chrome | $85 | $0 | 2% on gas, 2% on dining (up to $4,000 a year combined, then 1%); 1% on everything else | 16.74%–25.74% variable APR | Not published |
| 5. Bank of America® Customized Cash Rewards Credit Card for Students | $84 | $0 | 2% (up to $10,000 a year) on groceries; 1% on everything else | 17.74%–27.74% variable APR | Not published |
Check eligibility, merchant restrictions and sources for our pick
- Capital One Savor Student Cash Rewards Credit Card
Eligibility: Students enrolled, or admitted and enrolling within three months, at an accredited university, community college or other higher education institution Product page (checked 2026-10-22).
Annual fee: $0. Product page (checked 2026-10-22). Rewards source: Product page (checked 2026-10-22).
We include cards whose issuer says, on its own page, that the card is for students. An example of a student’s monthly spending. It is illustrative, not a statistic. 6 cards compared. How we compare cards
Best credit cards for groceries
Among the credit cards for groceries in our records, the Citizens Summit® World Mastercard® is worth the most on our example grocery-heavy household spending of $1,730 a month: $482 a year after fees.
Our pick for credit cards for groceries: Citizens Summit® World Mastercard®
Why it wonThe Citizens Summit® World Mastercard® is worth $482 a year on the example spending ($482 in rewards, $0 annual fee), the most of the 21 cards we could value for this need.
The catchEverything outside dining and groceries earns 1.5%, so against a flat 2% card you need more than $5,000 a year at restaurants and grocery stores for every $10,000 you spend elsewhere just to break even.
Who shouldn’t get the Citizens Summit® World Mastercard®: see our pick for cash back credit cards, the same card.
If the Citizens Summit® World Mastercard® doesn’t suit you, the next-best of the credit cards for groceries on the same grocery-heavy household spending is the Navy Federal More Rewards American Express® Card, worth $472 a year after fees ($11 less).
| Card | Worth a year after fees | Annual fee | At grocery stores | Rewards | Standard APR |
|---|---|---|---|---|---|
| 1. Citizens Summit® World Mastercard® | $482 | $0 | 3% | 3% on dining, groceries; 1.5% on everything else | 17.49%–27.49% variable APR |
| 2. Navy Federal More Rewards American Express® Card | $472 | $0 | 3x points | 3x points on dining, groceries, gas, transit; 1x points on everything else | 14.15%–18% variable APR |
| 3. Blue Cash Preferred® Card from American Express | $467 | $0 the first year, then $95 | 6% on up to $6,000 a year, then 1% | 6% (up to $6,000 a year) on groceries; 6% on streaming; 3% on transit, gas; 1% on everything else | Not published |
| 4. Capital One Savor Cash Rewards Credit Card | $443 | $0 | 3% | 3% on groceries, dining, entertainment, streaming; 1% on everything else | 18.74%–28.74% variable APR |
| 5. Capital One Savor Student Cash Rewards Credit Card | $443 | $0 | 3% | 3% on groceries, dining, entertainment, streaming; 1% on everything else | 18.74%–28.74% variable APR |
Check eligibility, merchant restrictions and sources for our pick
- Citizens Summit® World Mastercard®
Eligibility: Not established from our sources; check with the issuer.
Annual fee: $0. Rates and Fees Table (Schumer box) (checked 2026-10-06). Rewards source: Product page (checked 2026-10-06).
groceries restrictions: eligible purchases made in the restaurant and grocery store (excluding Walmart® and select superstores) merchant categories Rates and Fees Table (Schumer box) (checked 2026-10-06).
When does a different card win for groceries?
On $800 a month of groceries spending, Blue Cash Preferred® Card from American Express leads when this is the only spending on the card, after its full ongoing annual fee. Include the example’s other $930 a month and Citizens Summit® World Mastercard® leads. We compared 60 approved cards for groceries, flat-rate cards included, on rewards after fees when you pay in full; a tie means equal annual values to the cent. How we test.
Compare spending scenarios and see when the winner changes
| Monthly groceries spend | Only this category on the card | All example spending on one card |
|---|---|---|
| $100 | Tie A (6 cards)$36 a year after fee | Tie B (9 cards)$247.20 a year after fee |
| $250 | Tie A (6 cards)$90 a year after fee | Citizens Summit® World Mastercard®$284.40 a year after fee |
| $500 | Blue Cash Preferred® Card from American Express$265 a year after fee | Blue Cash Preferred® Card from American Express$430.60 a year after fee |
| $750 | Blue Cash Preferred® Card from American Express$295 a year after fee | Citizens Summit® World Mastercard®$464.40 a year after fee |
| $800 (example) | Blue Cash Preferred® Card from American Express$301 a year after fee | Citizens Summit® World Mastercard®$482.40 a year after fee |
| $1,000 | Tie C (5 cards)$360 a year after fee | Citizens Summit® World Mastercard®$554.40 a year after fee |
| $1,500 | Tie C (5 cards)$540 a year after fee | Citizens Summit® World Mastercard®$734.40 a year after fee |
| $2,000 | Tie C (5 cards)$720 a year after fee | Citizens Summit® World Mastercard®$914.40 a year after fee |
The columns use different total spending, so don’t read the gap between them as the gain from a second card. The category-only column charges the full annual fee to groceries.
Spending ranges that change the whole-wallet winner
Tested at every whole dollar from $1 to $2,000 a month of groceries, with other spending fixed.
| Monthly groceries spend tested | Leading card or tied cards |
|---|---|
| $1–$239 | Tie B (9 cards) |
| $240 | Tie D (10 cards) |
| $241–$343 | Citizens Summit® World Mastercard® |
| $344–$734 | Blue Cash Preferred® Card from American Express |
| $735–$2,000 | Citizens Summit® World Mastercard® |
Tied cards, each at the same annual value to the cent:
- Tie A: Blue Cash Everyday® Card from American Express / Capital One Savor Cash Rewards Credit Card / Capital One Savor Student Cash Rewards Credit Card / Citizens Summit® World Mastercard® / Navy Federal More Rewards American Express® Card / Upgrade OneCard Essentials
- Tie B: Citi Double Cash® Card / Credit One Bank Omni Rewards American Express® Card / Fifth Third Preferred Cash/Back Card / Navy Federal cashRewards Plus Credit Card / PNC Cash Unlimited® Visa Signature® Credit Card / Synchrony Premier World Mastercard® / TD Double Up℠ Credit Card / U.S. Bank Smartly™ Visa Signature® Card / Wells Fargo Active Cash® Card
- Tie C: Capital One Savor Cash Rewards Credit Card / Capital One Savor Student Cash Rewards Credit Card / Citizens Summit® World Mastercard® / Navy Federal More Rewards American Express® Card / Upgrade OneCard Essentials
- Tie D: Citi Double Cash® Card / Citizens Summit® World Mastercard® / Credit One Bank Omni Rewards American Express® Card / Fifth Third Preferred Cash/Back Card / Navy Federal cashRewards Plus Credit Card / PNC Cash Unlimited® Visa Signature® Credit Card / Synchrony Premier World Mastercard® / TD Double Up℠ Credit Card / U.S. Bank Smartly™ Visa Signature® Card / Wells Fargo Active Cash® Card
Reproduce these results: spending, restrictions and sources
Monthly example: groceries: $800; dining: $150; gas: $150; streaming: $30; online shopping: $100; everything else: $500. Only groceries changes in the ranges above. For travel, the example’s proportions of flights, hotels and other travel stay fixed. Recorded rewards caps apply.
Sources for the cards that lead at any tested amount (fee and rewards terms; eligibility and restrictions for each pick are in the picks table):
- Capital One Savor Cash Rewards Credit Card: $0. Product page (checked 2026-10-22). Product page (checked 2026-10-22).
- Blue Cash Everyday® Card from American Express: $0. Product page (checked 2026-10-04). Card Member Agreement (as of October 8, 2025) (checked 2026-10-05).
- Blue Cash Preferred® Card from American Express: $0 the first year, then $95. Product page (checked 2026-10-04). Card Member Agreement (as of October 8, 2025) (checked 2026-10-05).
- Capital One Savor Student Cash Rewards Credit Card: $0. Product page (checked 2026-10-22). Product page (checked 2026-10-22).
- Navy Federal More Rewards American Express® Card: $0. Product page, including its Rates and Fees panels and footnotes (checked 2026-10-06). Rewards Program Description (NFCU 829B) (checked 2026-10-06).
- Citizens Summit® World Mastercard®: $0. Rates and Fees Table (Schumer box) (checked 2026-10-06). Product page (checked 2026-10-06). Rates and Fees Table (Schumer box) (checked 2026-10-06).
- Upgrade OneCard Essentials: $0. Important Disclosures (Schumer box, offer code CC_01) (checked 2026-10-06). Merchant categories page (checked 2026-10-06).
- Wells Fargo Active Cash® Card: $0. Important Credit Terms (pricing table) (checked 2026-10-04). Product page (checked 2026-10-04).
- Citi Double Cash® Card: $0. Product page, including its Pricing Details (checked 2026-10-05).
- U.S. Bank Smartly™ Visa Signature® Card: $0. Terms and conditions (Schumer box) (checked 2026-10-05). Product page (checked 2026-10-05).
- PNC Cash Unlimited® Visa Signature® Credit Card: $0. Product page (checked 2026-10-06). Rewards Terms & Conditions (checked 2026-10-06).
- TD Double Up℠ Credit Card: $0. Product page, including its Rates and fees table (checked 2026-10-06). Important Credit Card Terms and Conditions (Schumer box and rewards agreement) (checked 2026-10-06).
- Navy Federal cashRewards Plus Credit Card: $0. Product page, including its Rates and Fees panels and footnotes (checked 2026-10-06).
- Synchrony Premier World Mastercard®: $0. Synchrony Mastercards page (rates and fees footnote) (checked 2026-10-22). Synchrony Premier World Mastercard Rewards Terms (checked 2026-10-06).
- Fifth Third Preferred Cash/Back Card: $0. Product page: Notices & Disclosures (rates and fees) (checked 2026-10-06).
- Credit One Bank Omni Rewards American Express® Card: $0. Terms, fees & conditions (Schumer box, eligibility criteria and rewards program terms) (checked 2026-10-06).
We include cards whose issuer says, on its own page, that the card earns a higher reward rate at grocery stores or supermarkets than on everyday spending. An example of a household whose biggest spending is groceries. It is illustrative, not a statistic. 21 cards compared; 19 more considered and left out. How we compare cards
Best credit cards for gas
Among the credit cards for gas in our records, the Blue Cash Preferred® Card from American Express is worth the most on our example commuting household spending of $1,470 a month: $429 a year after fees.
Our pick for credit cards for gas: Blue Cash Preferred® Card from American Express
Why it wonThe Blue Cash Preferred® Card from American Express is worth $429 a year on the example spending ($524 in rewards, $95 annual fee), the most of the 21 cards we could value for this need.
The catchFrom the second year it costs $95, and the 6% grocery rate drops to 1% after $6,000 a year.
Not for: Anyone who spends little at U.S. supermarkets, because the $95 fee from year two can outweigh the extra cash back, and anyone who spends abroad (2.7% foreign transaction fee).
If the Blue Cash Preferred® Card from American Express doesn’t suit you, the next-best of the credit cards for gas on the same commuting household spending is the Navy Federal More Rewards American Express® Card, worth $404 a year after fees ($25 less).
| Card | Worth a year after fees | Annual fee | At gas stations | Rewards | Standard APR |
|---|---|---|---|---|---|
| 1. Blue Cash Preferred® Card from American Express | $429 | $0 the first year, then $95 | 3% | 6% (up to $6,000 a year) on groceries; 6% on streaming; 3% on transit, gas; 1% on everything else | Not published |
| 2. Navy Federal More Rewards American Express® Card | $404 | $0 | 3x points | 3x points on dining, groceries, gas, transit; 1x points on everything else | 14.15%–18% variable APR |
| 3. Upgrade OneCard Essentials | $373 | $0 | 3% | 3% on gas, groceries, streaming; 1% on everything else | 19.99%–29.99% variable APR |
| 4. Blue Cash Everyday® Card from American Express | $368 | $0 | 3% on up to $6,000 a year, then 1% | 3% (up to $6,000 a year each) on groceries, online shopping, gas; 1% on everything else | Not published |
| 5. Costco Anywhere Visa® Card by Citi | $356 | $0 | 4% on up to $7,000 a year, then 1% | 4% (up to $7,000 a year) on gas; 3% on dining, travel; 1% on everything else | 18.99%–26.99% variable APR |
Check eligibility, merchant restrictions and sources for our pick
- Blue Cash Preferred® Card from American Express
Eligibility: Not established from our sources; check with the issuer.
Annual fee: $0 the first year, then $95. Product page (checked 2026-10-04). Rewards source: Product page (checked 2026-10-04).
gas restrictions: gasoline at gasoline stations located in the U.S. (superstores, supermarkets and warehouse clubs that sell gasoline are not considered gas stations) Card Member Agreement (as of October 8, 2025) (checked 2026-10-05).
When does a different card win for gas?
On $400 a month of gas spending, Costco Anywhere Visa® Card by Citi / PNC Cash Rewards® Visa® Credit Card leads when this is the only spending on the card, after its full ongoing annual fee. Include the example’s other $1,070 a month and Blue Cash Preferred® Card from American Express leads. We compared 60 approved cards for gas, flat-rate cards included, on rewards after fees when you pay in full; a tie means equal annual values to the cent. How we test.
Compare spending scenarios and see when the winner changes
| Monthly gas spend | Only this category on the card | All example spending on one card |
|---|---|---|
| $100 | Costco Anywhere Visa® Card by Citi / PNC Cash Rewards® Visa® Credit Card$48 a year after fee | Blue Cash Preferred® Card from American Express$321.40 a year after fee |
| $250 | Costco Anywhere Visa® Card by Citi / PNC Cash Rewards® Visa® Credit Card$120 a year after fee | Blue Cash Preferred® Card from American Express$375.40 a year after fee |
| $400 (example) | Costco Anywhere Visa® Card by Citi / PNC Cash Rewards® Visa® Credit Card$192 a year after fee | Blue Cash Preferred® Card from American Express$429.40 a year after fee |
| $500 | Costco Anywhere Visa® Card by Citi / PNC Cash Rewards® Visa® Credit Card$240 a year after fee | Blue Cash Preferred® Card from American Express$465.40 a year after fee |
| $750 | Credit One Bank Wander® American Express® Card$355 a year after fee | Blue Cash Preferred® Card from American Express / Credit One Bank Wander® American Express® Card$555.40 a year after fee |
| $1,000 | Credit One Bank Wander® American Express® Card$505 a year after fee | Credit One Bank Wander® American Express® Card$705.40 a year after fee |
| $1,500 | Credit One Bank Wander® American Express® Card$805 a year after fee | Credit One Bank Wander® American Express® Card$1,005.40 a year after fee |
| $2,000 | Credit One Bank Wander® American Express® Card$1,105 a year after fee | Credit One Bank Wander® American Express® Card$1,305.40 a year after fee |
The columns use different total spending, so don’t read the gap between them as the gain from a second card. The category-only column charges the full annual fee to gas.
Spending ranges that change the whole-wallet winner
Tested at every whole dollar from $1 to $2,000 a month of gas, with other spending fixed.
| Monthly gas spend tested | Leading card or tied cards |
|---|---|
| $1–$749 | Blue Cash Preferred® Card from American Express |
| $750 | Blue Cash Preferred® Card from American Express / Credit One Bank Wander® American Express® Card |
| $751–$2,000 | Credit One Bank Wander® American Express® Card |
Reproduce these results: spending, restrictions and sources
Monthly example: gas: $400; groceries: $400; dining: $150; streaming: $20; everything else: $500. Only gas changes in the ranges above. For travel, the example’s proportions of flights, hotels and other travel stay fixed. Recorded rewards caps apply.
Sources for the cards that lead at any tested amount (fee and rewards terms; eligibility and restrictions for each pick are in the picks table):
- Blue Cash Preferred® Card from American Express: $0 the first year, then $95. Product page (checked 2026-10-04). Card Member Agreement (as of October 8, 2025) (checked 2026-10-05).
- Costco Anywhere Visa® Card by Citi: $0. Product page, including its Pricing Details (checked 2026-10-05).
- PNC Cash Rewards® Visa® Credit Card: $0. Product page (checked 2026-10-06). Rewards Terms & Conditions (checked 2026-10-06). Rewards Terms & Conditions (checked 2026-10-06).
- Credit One Bank Wander® American Express® Card: $95. Terms, fees & conditions (Schumer box, eligibility criteria and rewards program terms) (checked 2026-10-06).
We include cards whose issuer says, on its own page, that the card earns a higher reward rate at gas stations than on everyday spending. An example of a household that drives a lot, so gas is one of its biggest costs. It is illustrative, not a statistic. 21 cards compared; 13 more considered and left out. How we compare cards
Best no annual fee credit cards
Among the no annual fee credit cards in our records, the Citizens Summit® World Mastercard® is worth the most on our example everyday household spending of $1,400 a month: $342 a year after fees.
Our pick for no annual fee credit cards: Citizens Summit® World Mastercard®
Why it wonThe Citizens Summit® World Mastercard® is worth $342 a year on the example spending ($342 in rewards, $0 annual fee), the most of the 65 cards we could value for this need.
The catchEverything outside dining and groceries earns 1.5%, so against a flat 2% card you need more than $5,000 a year at restaurants and grocery stores for every $10,000 you spend elsewhere just to break even.
Who shouldn’t get the Citizens Summit® World Mastercard®: see our pick for cash back credit cards, the same card.
If the Citizens Summit® World Mastercard® doesn’t suit you, the next-best of the no annual fee credit cards on the same everyday household spending is the Citi Double Cash® Card, worth $336 a year after fees ($6 less).
| Card | Worth a year after fees | Annual fee | Rewards | Standard APR | Foreign transaction fee |
|---|---|---|---|---|---|
| 1. Citizens Summit® World Mastercard® | $342 | $0 | 3% on dining, groceries; 1.5% on everything else | 17.49%–27.49% variable APR | 3% |
| 2. Citi Double Cash® Card | $336 | $0 | 2% on everything | 18.49%–28.74% variable APR | 3% |
| 3. Credit One Bank Omni Rewards American Express® Card | $336 | $0 | 2% on everything | 29.74% variable APR | None |
| 4. Fifth Third Preferred Cash/Back Card | $336 | $0 | 2% on everything | 19.24%–29.24% variable APR | None |
| 5. Navy Federal cashRewards Plus Credit Card | $336 | $0 | 2% on everything | 14.15%–18% variable APR | None |
Check eligibility, merchant restrictions and sources for our pick
- Citizens Summit® World Mastercard®
Eligibility: Not established from our sources; check with the issuer.
Annual fee: $0. Rates and Fees Table (Schumer box) (checked 2026-10-06). Rewards source: Product page (checked 2026-10-06).
We include every card in our records whose issuer states, in its own terms or on its product page, that the card has no annual fee. Cards that are free only in the first year are left out. An example of ordinary spending spread across the usual categories, with no single category dominating. It is illustrative, not a statistic. 98 cards compared, 33 of them not ranked because our record lacks a figure needed for the calculation; 1 more considered and left out. How we compare cards
Best credit cards for dining
Among the credit cards for dining in our records, the Citizens Summit® World Mastercard® is worth the most on our example dining-heavy spending of $1,370 a month: $373 a year after fees.
Our pick for credit cards for dining: Citizens Summit® World Mastercard®
Why it wonThe Citizens Summit® World Mastercard® is worth $373 a year on the example spending ($373 in rewards, $0 annual fee), the most of the 23 cards we could value for this need.
The catchEverything outside dining and groceries earns 1.5%, so against a flat 2% card you need more than $5,000 a year at restaurants and grocery stores for every $10,000 you spend elsewhere just to break even.
Who shouldn’t get the Citizens Summit® World Mastercard®: see our pick for cash back credit cards, the same card.
If the Citizens Summit® World Mastercard® doesn’t suit you, the next-best of the credit cards for dining on the same dining-heavy spending is the Navy Federal More Rewards American Express® Card, worth $356 a year after fees ($16 less).
| Card | Worth a year after fees | Annual fee | Dining | Rewards | Standard APR |
|---|---|---|---|---|---|
| 1. Citizens Summit® World Mastercard® | $373 | $0 | 3% | 3% on dining, groceries; 1.5% on everything else | 17.49%–27.49% variable APR |
| 2. Navy Federal More Rewards American Express® Card | $356 | $0 | 3x points | 3x points on dining, groceries, gas, transit; 1x points on everything else | 14.15%–18% variable APR |
| 3. Capital One Savor Cash Rewards Credit Card | $349 | $0 | 3% | 3% on groceries, dining, entertainment, streaming; 1% on everything else | 18.74%–28.74% variable APR |
| 4. Capital One Savor Student Cash Rewards Credit Card | $349 | $0 | 3% | 3% on groceries, dining, entertainment, streaming; 1% on everything else | 18.74%–28.74% variable APR |
| 5. Chase Freedom Unlimited® Credit Card | $319 | $0 | 3% | 3% on dining, drugstores; 1.5% on everything else | 18.49%–27.99% variable APR |
Check eligibility, merchant restrictions and sources for our pick
- Citizens Summit® World Mastercard®
Eligibility: Not established from our sources; check with the issuer.
Annual fee: $0. Rates and Fees Table (Schumer box) (checked 2026-10-06). Rewards source: Product page (checked 2026-10-06).
dining restrictions: eligible purchases made in the restaurant and grocery store (excluding Walmart® and select superstores) merchant categories Rates and Fees Table (Schumer box) (checked 2026-10-06).
When does a different card win for dining?
On $400 a month of dining spending, Credit One Bank Wander® American Express® Card leads when this is the only spending on the card, after its full ongoing annual fee. Include the example’s other $970 a month and Citizens Summit® World Mastercard® leads. We compared 62 approved cards for dining, flat-rate cards included, on rewards after fees when you pay in full; a tie means equal annual values to the cent. How we test.
Compare spending scenarios and see when the winner changes
| Monthly dining spend | Only this category on the card | All example spending on one card |
|---|---|---|
| $100 | Tie A (11 cards)$36 a year after fee | Citizens Summit® World Mastercard®$264.60 a year after fee |
| $250 | Tie A (11 cards)$90 a year after fee | Citizens Summit® World Mastercard®$318.60 a year after fee |
| $400 (example) | Credit One Bank Wander® American Express® Card$145 a year after fee | Citizens Summit® World Mastercard®$372.60 a year after fee |
| $500 | Credit One Bank Wander® American Express® Card$205 a year after fee | Citizens Summit® World Mastercard®$408.60 a year after fee |
| $750 | Credit One Bank Wander® American Express® Card$355 a year after fee | Credit One Bank Wander® American Express® Card$519.40 a year after fee |
| $1,000 | Credit One Bank Wander® American Express® Card$505 a year after fee | Credit One Bank Wander® American Express® Card$669.40 a year after fee |
| $1,500 | Credit One Bank Wander® American Express® Card$805 a year after fee | Credit One Bank Wander® American Express® Card$969.40 a year after fee |
| $2,000 | Credit One Bank Wander® American Express® Card$1,105 a year after fee | Credit One Bank Wander® American Express® Card$1,269.40 a year after fee |
The columns use different total spending, so don’t read the gap between them as the gain from a second card. The category-only column charges the full annual fee to dining.
Spending ranges that change the whole-wallet winner
Tested at every whole dollar from $1 to $2,000 a month of dining, with other spending fixed.
| Monthly dining spend tested | Leading card or tied cards |
|---|---|
| $1–$34 | Tie B (9 cards) |
| $35 | Tie C (10 cards) |
| $36–$663 | Citizens Summit® World Mastercard® |
| $664–$2,000 | Credit One Bank Wander® American Express® Card |
Tied cards, each at the same annual value to the cent:
- Tie A: Capital One Savor Cash Rewards Credit Card / Capital One Savor Student Cash Rewards Credit Card / Chase Freedom Flex® Credit Card / Chase Freedom Unlimited® Credit Card / Costco Anywhere Visa® Card by Citi / Citizens Summit® World Mastercard® / Mission Lane Gold Line Visa® / Navy Federal More Rewards American Express® Card / PNC Cash Rewards® Visa® Credit Card / TD Cash Credit Card / Wells Fargo Autograph® Card
- Tie B: Citi Double Cash® Card / Credit One Bank Omni Rewards American Express® Card / Fifth Third Preferred Cash/Back Card / Navy Federal cashRewards Plus Credit Card / PNC Cash Unlimited® Visa Signature® Credit Card / Synchrony Premier World Mastercard® / TD Double Up℠ Credit Card / U.S. Bank Smartly™ Visa Signature® Card / Wells Fargo Active Cash® Card
- Tie C: Citi Double Cash® Card / Citizens Summit® World Mastercard® / Credit One Bank Omni Rewards American Express® Card / Fifth Third Preferred Cash/Back Card / Navy Federal cashRewards Plus Credit Card / PNC Cash Unlimited® Visa Signature® Credit Card / Synchrony Premier World Mastercard® / TD Double Up℠ Credit Card / U.S. Bank Smartly™ Visa Signature® Card / Wells Fargo Active Cash® Card
Reproduce these results: spending, restrictions and sources
Monthly example: dining: $400; groceries: $300; gas: $100; entertainment: $50; streaming: $20; everything else: $500. Only dining changes in the ranges above. For travel, the example’s proportions of flights, hotels and other travel stay fixed. Recorded rewards caps apply.
Sources for the cards that lead at any tested amount (fee and rewards terms; eligibility and restrictions for each pick are in the picks table):
- Wells Fargo Autograph® Card: $0. Important Credit Terms (pricing table) (checked 2026-10-05). Product page (checked 2026-10-05). Product page (checked 2026-10-05).
- Capital One Savor Cash Rewards Credit Card: $0. Product page (checked 2026-10-22). Product page (checked 2026-10-22).
- Chase Freedom Unlimited® Credit Card: $0. Product page (checked 2026-10-04). Product page (checked 2026-10-04).
- Capital One Savor Student Cash Rewards Credit Card: $0. Product page (checked 2026-10-22). Product page (checked 2026-10-22).
- Costco Anywhere Visa® Card by Citi: $0. Product page, including its Pricing Details (checked 2026-10-05). Product page, including its Pricing Details (checked 2026-10-05).
- Chase Freedom Flex® Credit Card: $0. Pricing and terms (Schumer box) (checked 2026-10-06). Rewards program agreement (checked 2026-10-06). Rewards category FAQ (checked 2026-10-05).
- PNC Cash Rewards® Visa® Credit Card: $0. Product page (checked 2026-10-06). Rewards Terms & Conditions (checked 2026-10-06). Rewards Terms & Conditions (checked 2026-10-06).
- TD Cash Credit Card: $0. Product page, including its Rates and fees table (checked 2026-10-22). Product page, including its Rates and fees table (checked 2026-10-22).
- Navy Federal More Rewards American Express® Card: $0. Product page, including its Rates and Fees panels and footnotes (checked 2026-10-06). Rewards Program Description (NFCU 829B) (checked 2026-10-06). Product page, including its Rates and Fees panels and footnotes (checked 2026-10-06).
- Citizens Summit® World Mastercard®: $0. Rates and Fees Table (Schumer box) (checked 2026-10-06). Product page (checked 2026-10-06). Rates and Fees Table (Schumer box) (checked 2026-10-06).
- Credit One Bank Wander® American Express® Card: $95. Terms, fees & conditions (Schumer box, eligibility criteria and rewards program terms) (checked 2026-10-06).
- Mission Lane Gold Line Visa®: $0. Product page (checked 2026-10-06). Cash Back Program Terms (3% travel, dining and gas, issued by TAB Bank) (checked 2026-10-06). Cash Back Program Terms (3% travel, dining and gas, issued by TAB Bank) (checked 2026-10-06).
- Wells Fargo Active Cash® Card: $0. Important Credit Terms (pricing table) (checked 2026-10-04). Product page (checked 2026-10-04).
- Citi Double Cash® Card: $0. Product page, including its Pricing Details (checked 2026-10-05).
- U.S. Bank Smartly™ Visa Signature® Card: $0. Terms and conditions (Schumer box) (checked 2026-10-05). Product page (checked 2026-10-05).
- PNC Cash Unlimited® Visa Signature® Credit Card: $0. Product page (checked 2026-10-06). Rewards Terms & Conditions (checked 2026-10-06).
- TD Double Up℠ Credit Card: $0. Product page, including its Rates and fees table (checked 2026-10-06). Important Credit Card Terms and Conditions (Schumer box and rewards agreement) (checked 2026-10-06).
- Navy Federal cashRewards Plus Credit Card: $0. Product page, including its Rates and Fees panels and footnotes (checked 2026-10-06).
- Synchrony Premier World Mastercard®: $0. Synchrony Mastercards page (rates and fees footnote) (checked 2026-10-22). Synchrony Premier World Mastercard Rewards Terms (checked 2026-10-06).
- Fifth Third Preferred Cash/Back Card: $0. Product page: Notices & Disclosures (rates and fees) (checked 2026-10-06).
- Credit One Bank Omni Rewards American Express® Card: $0. Terms, fees & conditions (Schumer box, eligibility criteria and rewards program terms) (checked 2026-10-06).
We include cards whose issuer says, on its own page, that the card earns a higher reward rate on dining at restaurants than on everyday spending. An example of someone who eats out or orders in often. It is illustrative, not a statistic. 23 cards compared; 24 more considered and left out. How we compare cards
Best travel credit cards
Among the travel credit cards in our records, the Credit One Bank Wander® American Express® Card is worth the most on our example travel-heavy spending of $2,070 a month: $609 a year after fees.
Our pick for travel credit cards: Credit One Bank Wander® American Express® Card
Why it wonThe Credit One Bank Wander® American Express® Card is worth $609 a year on the example spending ($704 in rewards, $95 annual fee), the most of the 10 cards we could value for this need.
The catchThe $95 annual fee is billed when the account opens, so a $400 credit line starts with about $305 available, and the 10-point hotel and car rate needs bookings through Credit One’s travel provider.
Not for: Anyone who spends less than about $2,375 a year on travel, dining and gas: below that, the extra 4 points per dollar don’t cover the $95 fee compared with a no-fee 1% card. Also anyone who carries a balance, at a 29.74% variable APR.
If the Credit One Bank Wander® American Express® Card doesn’t suit you, the next-best of the travel credit cards on the same travel-heavy spending is the Costco Anywhere Visa® Card by Citi, worth $494 a year after fees ($115 less).
| Card | Worth a year after fees | Annual fee | Travel | Rewards | Foreign transaction fee |
|---|---|---|---|---|---|
| 1. Credit One Bank Wander® American Express® Card | $609 | $95 | 5x points on flights; 5x points on hotels; 5x points on other travel | 5x points on travel, dining, gas; 1x points on everything else | None |
| 2. Costco Anywhere Visa® Card by Citi | $494 | $0 | 3% on flights; 3% on hotels; 3% on other travel | 4% (up to $7,000 a year) on gas; 3% on dining, travel; 1% on everything else | None |
| 3. Wells Fargo Autograph® Card | $481 | $0 | 3x points on flights; 3x points on hotels; 3x points on other travel | 3x points on dining, travel, gas, transit, streaming; 1x points on everything else | None |
| 4. Mission Lane Gold Line Visa® | $476 | $0 | 3% on flights; 3% on hotels; 3% on other travel | 3% on gas, dining, travel, transit; 1% on everything else | None |
| 5. Navy Federal Flagship Premier Visa Signature® Credit Card | $405 | $95 | 4x points on flights; 4x points on hotels; 4x points on other travel | 4x points on travel, transit; 3x points on dining; 1x points on everything else | None |
Check eligibility, merchant restrictions and sources for our pick
- Credit One Bank Wander® American Express® Card
Eligibility: Average to excellent credit, as Credit One recommends it. Credit One says you may not qualify if you already have an open or unpaid Credit One account or a pending application, live in a U.S. territory, have an APO/FPO address, or are covered by the Military Lending Act. Terms, fees & conditions (Schumer box, eligibility criteria and rewards program terms) (checked 2026-10-06).
Annual fee: $95. Terms, fees & conditions (Schumer box, eligibility criteria and rewards program terms) (checked 2026-10-06). Rewards source: Terms, fees & conditions (Schumer box, eligibility criteria and rewards program terms) (checked 2026-10-06).
When does a different card win for travel?
On $500 a month of travel spending, Credit One Bank Wander® American Express® Card leads when this is the only spending on the card, after its full ongoing annual fee. Include the example’s other $1,570 a month and Credit One Bank Wander® American Express® Card leads—the same result for both uses. We compared 49 approved cards for travel, flat-rate cards included, on rewards after fees when you pay in full; a tie means equal annual values to the cent. How we test.
Compare spending scenarios and see when the winner changes
| Monthly travel spend | Only this category on the card | All example spending on one card |
|---|---|---|
| $100 | Costco Anywhere Visa® Card by Citi / Mission Lane Gold Line Visa® / Wells Fargo Autograph® Card$36 a year after fee | Tie A (9 cards)$400.80 a year after fee |
| $250 | Costco Anywhere Visa® Card by Citi / Mission Lane Gold Line Visa® / Wells Fargo Autograph® Card$90 a year after fee | Credit One Bank Wander® American Express® Card$459.40 a year after fee |
| $500 (example) | Credit One Bank Wander® American Express® Card$205 a year after fee | Credit One Bank Wander® American Express® Card$609.40 a year after fee |
| $750 | Credit One Bank Wander® American Express® Card$355 a year after fee | Credit One Bank Wander® American Express® Card$759.40 a year after fee |
| $1,000 | Credit One Bank Wander® American Express® Card$505 a year after fee | Credit One Bank Wander® American Express® Card$909.40 a year after fee |
| $1,500 | Credit One Bank Wander® American Express® Card$805 a year after fee | Credit One Bank Wander® American Express® Card$1,209.40 a year after fee |
| $2,000 | Credit One Bank Wander® American Express® Card$1,105 a year after fee | Credit One Bank Wander® American Express® Card$1,509.40 a year after fee |
The columns use different total spending, so don’t read the gap between them as the gain from a second card. The category-only column charges the full annual fee to travel.
Spending ranges that change the whole-wallet winner
Tested at every whole dollar from $1 to $2,000 a month of travel, with other spending fixed.
| Monthly travel spend tested | Leading card or tied cards |
|---|---|
| $1–$187 | Tie A (9 cards) |
| $188–$2,000 | Credit One Bank Wander® American Express® Card |
Tied cards, each at the same annual value to the cent:
- Tie A: Citi Double Cash® Card / Credit One Bank Omni Rewards American Express® Card / Fifth Third Preferred Cash/Back Card / Navy Federal cashRewards Plus Credit Card / PNC Cash Unlimited® Visa Signature® Credit Card / Synchrony Premier World Mastercard® / TD Double Up℠ Credit Card / U.S. Bank Smartly™ Visa Signature® Card / Wells Fargo Active Cash® Card
Reproduce these results: spending, restrictions and sources
Monthly example: flights: $200; hotels: $150; travel: $150; dining: $300; groceries: $400; gas: $150; streaming: $20; everything else: $700. Only travel changes in the ranges above. For travel, the example’s proportions of flights, hotels and other travel stay fixed. Recorded rewards caps apply.
Sources for the cards that lead at any tested amount (fee and rewards terms; eligibility and restrictions for each pick are in the picks table):
- Wells Fargo Autograph® Card: $0. Important Credit Terms (pricing table) (checked 2026-10-05). Product page (checked 2026-10-05). Product page (checked 2026-10-05).
- Costco Anywhere Visa® Card by Citi: $0. Product page, including its Pricing Details (checked 2026-10-05). Product page, including its Pricing Details (checked 2026-10-05).
- Credit One Bank Wander® American Express® Card: $95. Terms, fees & conditions (Schumer box, eligibility criteria and rewards program terms) (checked 2026-10-06).
- Mission Lane Gold Line Visa®: $0. Product page (checked 2026-10-06). Cash Back Program Terms (3% travel, dining and gas, issued by TAB Bank) (checked 2026-10-06). Cash Back Program Terms (3% travel, dining and gas, issued by TAB Bank) (checked 2026-10-06).
- Wells Fargo Active Cash® Card: $0. Important Credit Terms (pricing table) (checked 2026-10-04). Product page (checked 2026-10-04).
- Citi Double Cash® Card: $0. Product page, including its Pricing Details (checked 2026-10-05).
- U.S. Bank Smartly™ Visa Signature® Card: $0. Terms and conditions (Schumer box) (checked 2026-10-05). Product page (checked 2026-10-05).
- PNC Cash Unlimited® Visa Signature® Credit Card: $0. Product page (checked 2026-10-06). Rewards Terms & Conditions (checked 2026-10-06).
- TD Double Up℠ Credit Card: $0. Product page, including its Rates and fees table (checked 2026-10-06). Important Credit Card Terms and Conditions (Schumer box and rewards agreement) (checked 2026-10-06).
- Navy Federal cashRewards Plus Credit Card: $0. Product page, including its Rates and Fees panels and footnotes (checked 2026-10-06).
- Synchrony Premier World Mastercard®: $0. Synchrony Mastercards page (rates and fees footnote) (checked 2026-10-22). Synchrony Premier World Mastercard Rewards Terms (checked 2026-10-06).
- Fifth Third Preferred Cash/Back Card: $0. Product page: Notices & Disclosures (rates and fees) (checked 2026-10-06).
- Credit One Bank Omni Rewards American Express® Card: $0. Terms, fees & conditions (Schumer box, eligibility criteria and rewards program terms) (checked 2026-10-06).
We include cards whose issuer says, on its own page or in its rewards terms, that the card earns more on travel than on everyday spending, and whose issuer states what its points are worth. We value points only at that stated rate, never at a higher value from transferring them to airlines or hotels, so a card whose issuer states no value (such as Capital One Venture) can’t be ranked here yet. An example of someone who travels several times a year, by air and with hotel stays. It is illustrative, not a statistic. 10 cards compared; 21 more considered and left out. How we compare cards
Do rewards cover the interest if you carry a balance?
No, not on an average balance. A year’s interest on the average US card balance of $4,350 at the Federal Reserve’s average APR of 22.36% comes to about $973. The highest example value after fee among our picks is $609 a year, and the median pick’s is $342, so the interest is 1.6 times the best pick’s value and 2.8 times the median’s. Pay in full each month and the rewards are yours; if you carry a balance, compare APRs and intro offers first.
The balance is the New York Fed’s credit card debt per consumer with a credit report at the end of December 2025, an average that includes people who pay in full. The APR is the Federal Reserve’s average for accounts charged interest in August 2026. The interest is simple interest on a balance held constant for a year (balance × APR): an illustration, not a quote. Issuers charge interest daily on your actual balance and set your APR within each card’s published range, based on your credit. Each pick’s value uses its own list’s example spending; the highest is the travel credit cards pick, on $2,070 a month.
If you already carry a balance, moving it can cost less than any card earns back. Our balance transfer calculator works out what moving yours would cost on each US card with a transfer offer, fee and interest included, at the monthly payment you can make.
- Interest a year
- Rewards minus fee a year
| Bar | APR | Dollars a year |
|---|---|---|
| Interest: Lowest APR in our records | 10.24% | $445 |
| Interest: Median lowest APR in our records | 19.49% | $848 |
| Interest: Federal Reserve average APR | 22.36% | $973 |
| Interest: Highest APR in our records | 35.99% | $1,566 |
| Rewards: Highest pick value after fee (travel credit cards) | Not applicable | $609 |
Sources: State Level Household Debt Statistics 2003-2025, Federal Reserve Bank of New York, February 2026 (credit card debt per consumer); Federal Reserve Board, G.19 Consumer Credit, Commercial Bank Interest Rate on Credit Card Plans, Accounts Assessed Interest, via FRED; the lowest, median lowest and highest published purchase APRs across our 137 approved US cards, checked automatically against issuers’ terms from October 4, 2026 to October 22, 2026; and the picks table (10 picks valued). Our calculation.
Paying off a carried balance can still leave a last interest charge: see residual interest. For how the average APR has moved, see the average credit card interest rate in our statistics.
How to choose a credit card from these picks
- Start with how you repay. If you carry a balance, rewards minus fees is not your net saving: interest is excluded, and on the average balance it outweighs every pick’s value (see the comparison). Use Cardnivo’s purchase-intro options or balance-transfer options, and compare fees and the APR after the offer ends.
- Check who can apply. Student status, a security deposit, bank relationships and membership can limit which card fits. Each need’s section shows the issuer’s stated restrictions; we do not predict approval.
- Compare the same spending. Enter what you spend in the calculator. A high category reward rate may earn less overall than a flat-rate card after caps and the annual fee.
Our Best Score is an editorial rating across several example profiles. The spending ranking uses annual rewards minus the ongoing fee, so the highest score and the highest value can differ. See both methods.
How the ranking works
- Your spending, by categoryWe apply each card’s reward rate to what you spend in each category, including spending caps.
- Minus the annual feeCards are ranked by what they’re worth every year, so a big welcome bonus can’t buy first place. Year-one value is shown separately.
- Every figure is datedRates and fees come from each issuer’s own pages, with the date we checked. A missing figure means a card isn’t ranked, not that it’s counted as zero.
What US issuers publish, from our records
We have recorded 141 approved cards from 28 issuers (Alliant Credit Union, American Express, Avant, Bank of America, Barclays, Capital One, Chase, Citi, Citizens, Column N.A., Credit One Bank, Discover, Fifth Third Bank, Goldman Sachs Bank USA, Salt Lake City Branch, Huntington Bank, KeyBank, Mission Lane, Navy Federal Credit Union, PNC Bank, PenFed Credit Union, Regions Bank, Synchrony Bank, TD Bank, Truist, U.S. Bank, Upgrade, Wells Fargo, opensky), with source checks from October 4, 2026 to October 22, 2026. That is the cards in our records, not the whole US market. For the whole market, see our US credit card statistics, charted from Federal Reserve data.
| What we checked | What we found |
|---|---|
| No annual fee | 99 of 141 cards (3 not published) |
| Standard APR | 10.24%–35.99% APR across 137 of 141 cards that publish it |
| One APR for everyone, not a range | 35 of 137 cards |
| No foreign transaction fee | 82 of 141 cards; 46 charge 3% or 2.7% or 2%; 13 not on the page we checked |
| Balance transfer fee not on the page we checked | 40 of 141 cards |
| Intro APR offer published | 67 of 141 cards |
| Need a refundable deposit | 20 of 141 cards, from $49 |
| Rewards not described | 61 of 141 cards |
Source: our records of 137 approved cards, from each issuer’s published terms. Each card counts equally; these are not weighted by account numbers or balances. Each bar counts cards whose highest published purchase APR falls in that 2-point band (lower bound included).
| Top APR | Cards |
|---|---|
| 16% to under 18% | 4 |
| 18% to under 20% | 6 |
| 20% to under 22% | 0 |
| 22% to under 24% | 1 |
| 24% to under 26% | 9 |
| 26% to under 28% | 42 |
| 28% to under 30% | 63 |
| 30% to under 32% | 0 |
| 32% to under 34% | 8 |
| 34% to under 36% | 4 |
Our records, in numbers
The rankings are only as good as the data. Ours is a dated record of each card, taken from the issuer’s own pages, with the issuer’s exact words behind every figure.
- 141
- US cards on this site, from Wells Fargo, Chase, Capital One, American Express, Discover, Bank of America, Citi, U.S. Bank, Barclays, PNC Bank, TD Bank, Navy Federal Credit Union, PenFed Credit Union, Goldman Sachs Bank USA, Salt Lake City Branch, Column N.A., Synchrony Bank, Truist, Citizens, Fifth Third Bank, Regions Bank, KeyBank, Huntington Bank, Credit One Bank, Mission Lane, Upgrade, opensky, Avant, and Alliant Credit Union
- 1985
- quotes from issuers behind our figures, each tested against a saved copy of the page
- 276
- dated copies of issuer pages and terms, kept as evidence
- 141 of 141
- cards approved for publication. Every figure is checked automatically, word for word, against a saved copy of the issuer’s terms.
- October 22, 2026
- the most recent check against an issuer’s page The oldest figure was checked October 4, 2026.
- 0
- cards we’re paid for. Commission never changes the order: the calculation has no input for it.
A missing figure means our record does not establish it; it is not evidence that the issuer withholds it. Check the source and recorded limitation. We never substitute zero for missing data.
For the US market as a whole, see our credit card statistics: debt, average APRs and late payments, charted from Federal Reserve data.
Who’s behind BestCreditCards
Matt Woodley, our editor, is accountable for every card record and recommendation. He has worked on international money transfers since 2020.
- Editorial policy: how we choose cards and check every figure.
- Corrections log: every published figure we’ve had to correct.
- About us, or write to team@bestcredit.cards.
Choose your market
Card rules and rate wording differ by country, so each market gets its own page, figures and disclosures. We open a market only once we’ve checked its cards against its own regulated disclosure.
- United States USD · APR, from the Schumer box (pricing table). You’re on this page.
- United Kingdom GBP · Representative APR, from the Summary box. Not open yet.
- Germany EUR · Effektiver Jahreszins, from the SECCI (Europäische Standardinformationen für Verbraucherkredite). Not open yet.
- Best credit cards in Canada CAD · Annual interest rate, from the Information box. Its page and calculator are open.
- Australia AUD · Purchase rate p.a., from the Key Facts Sheet. Not open yet.
- Best credit cards in Brazil (in Portuguese) BRL · Juros do rotativo, from the tabela de tarifas e taxas de juros do emissor. Its page and calculator are open.
- Best credit cards in New Zealand NZD · Purchase interest rate, from the the issuer’s interest rates and fees page. Its page and calculator are open.
These picks as an image
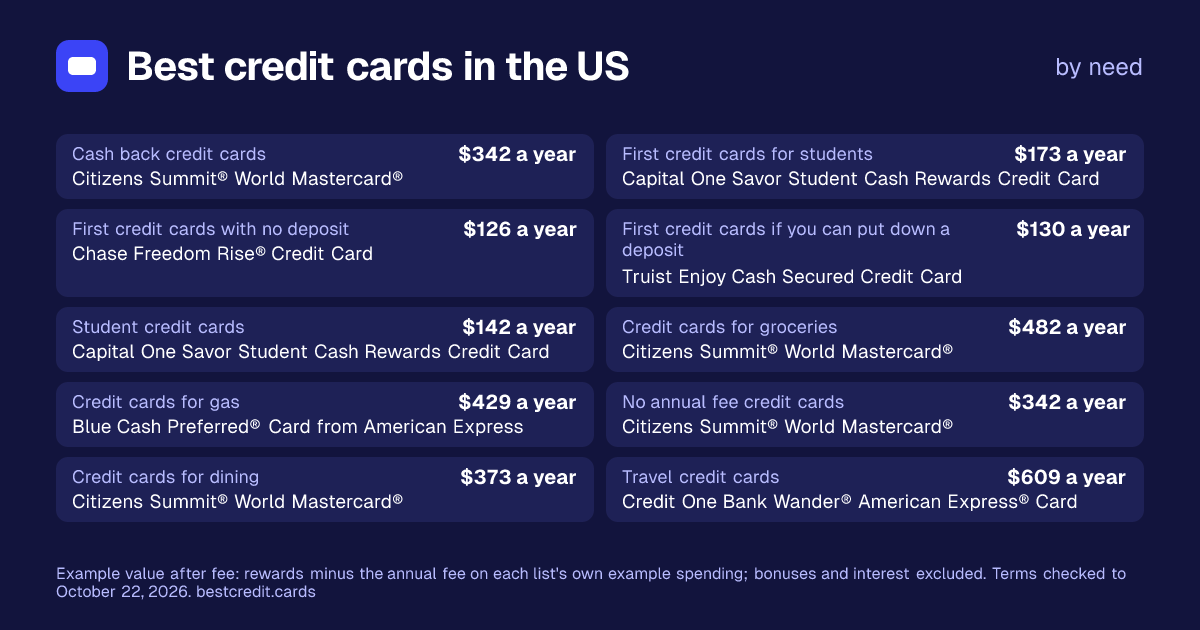
Approved for publication by Matt Woodley on October 6, 2026. Content updated October 27, 2026. Figures are checked automatically against a saved copy of each issuer’s terms. How we check every figure